Author: PJI Law, PLC

  • What is Commercial Litigation in Virginia?

    What is Commercial Litigation in Virginia?

    Business disagreements don’t always end with a difficult conversation or a revised contract. A customer may refuse to pay, a business partner may violate an agreement, or a shareholder may challenge how a company is being managed. When these types of conflicts can’t be resolved through negotiation, legal action may become necessary. At that point, many business owners begin asking: What is commercial litigation, and does it apply to my situation?

    Simply put, commercial litigation refers to the legal process of resolving business disputes through negotiation, alternative dispute resolution, or court proceedings. These cases can involve businesses, business owners, shareholders, partners, investors, or, in some situations, individuals involved in commercial transactions. While many commercial disputes settle before trial, others require a judge or jury to resolve complex legal issues.

    Whether you’re dealing with a breach of contract, allegations of fraud, shareholder disputes, or another business dispute, understanding the litigation process is the first step toward determining your legal options.

    At a Glance

    • Commercial litigation involves legal disputes arising from business relationships, contracts, and commercial transactions.
    • Common cases include breach of contract, business torts, shareholder disputes, partnership disputes, securities litigation, and intellectual property disputes.
    • The litigation process generally includes filing pleadings, exchanging evidence during discovery, negotiating settlement, and, if necessary, proceeding to trial.
    • Many commercial disputes are resolved through mediation or arbitration before reaching court.
    • Available remedies may include monetary damages, specific performance, injunctions, or other relief depending on the circumstances.
    • An experienced commercial litigation attorney can evaluate your situation, explain your options, and represent your interests throughout the dispute.

    What Is Commercial Litigation?

    Commercial litigation is a type of civil litigation involving disputes that arise from business activities. While civil litigation covers many different legal areas, commercial litigation focuses specifically on conflicts involving businesses, commercial transactions, contracts, and other business-related obligations.

    Because every dispute is different, commercial litigation refers to a broad spectrum of legal claims rather than a single type of lawsuit. Some cases involve two companies disputing the terms of a valid contract. Others may involve disagreements among business partners, allegations of fraud, claims involving intellectual property, or disputes between shareholders.

    Not every disagreement leads to a lawsuit. In many situations, legal counsel can negotiate a resolution before a dispute escalates. However, when informal efforts fail, filing a lawsuit may become the only option for protecting a company’s rights and valuable assets.

    A commercial litigation attorney helps clients understand the strengths and weaknesses of their position, identify available legal defenses, evaluate the possible consequences of different approaches, and develop a strategy that aligns with their business objectives.

    What Types of Business Disputes Can Lead to Commercial Litigation?

    Many different types of business disputes can lead to commercial litigation. The specific legal issues depend on the parties involved, the agreements that govern their relationship, and the facts surrounding the dispute. Many of these disputes are filed in the Fairfax Circuit Court, the 19th Judicial Circuit and the largest trial court in Virginia, which has general jurisdiction over civil business matters throughout Fairfax County and the City of Fairfax.

    Breach of Contract

    A breach of contract is one of the most common reasons businesses become involved in commercial litigation. A breach of contract occurs when one party fails to fulfill obligations established in a legally binding agreement. Depending on the circumstances, the issue may involve:

    • Failure to deliver goods or services
    • Nonpayment
    • Missed deadlines
    • Violations of confidentiality provisions
    • Failure to perform contractual obligations

    In many contract disputes, the court first determines whether a valid contract exists and whether the alleged breaching party failed to meet its legal obligations. If a breach is established, the available remedies may include monetary damages, specific performance, or other relief permitted under state law.

    Some commercial agreements also include liquidated damages clauses that establish in advance the amount one party must pay if certain contractual obligations are breached. Whether those provisions are enforceable depends on the contract language and applicable Virginia law.

    Because every agreement is unique, resolving a breach of contract often requires careful review of the contract language, communications between the parties, and the relevant documents surrounding the transaction.

    Partnership Disputes

    Business partners don’t always agree on how a company should operate. Partnership disputes frequently involve disagreements regarding:

    • Management authority
    • Ownership interests
    • Profit distributions
    • Breach of fiduciary duty
    • Dissolution of the business

    These disagreements can affect ongoing operations, strain business relationships, and expose the company to financial risk if they are not resolved promptly.

    Shareholder Disputes

    Closely held corporations often experience shareholder disputes involving voting rights, dividend distributions, corporate governance, minority shareholder rights, or allegations that majority owners acted improperly.

    When these conflicts arise, courts may examine corporate records, governing documents, and whether any shareholder violated a fiduciary duty owed to the company or other owners.

    Business Torts

    Unlike contract claims, business torts generally involve wrongful conduct that causes financial harm to another business or individual.

    Examples include:

    • Fraud claims
    • Negligent misrepresentation
    • Tortious interference with contracts or business relationships
    • Misappropriation of confidential information
    • Defamation affecting a business

    These wrongful actions often require extensive factual investigation before legal claims can be evaluated. Virginia courts also apply what’s known as the source-of-duty rule to distinguish a tort claim from a breach of contract claim.

    If the duty a party allegedly violated exists only because of the contract itself, the claim generally belongs in contract law, not tort law, and a party who suffers only disappointed economic expectations typically can’t recover on a tort theory for those losses. A tort claim usually requires a duty that exists independently of the contract, such as a duty owed under general law to protect persons or property.

    Intellectual Property Disputes

    Many businesses rely heavily on trademarks, copyrights, trade secrets, proprietary information, and other forms of intellectual property.

    Intellectual property disputes can arise when another party allegedly misuses protected materials or improperly benefits from another company’s innovations or branding.

    Resolving these disputes may involve contract law, intellectual property law, and other legal principles depending on the specific circumstances.

    Securities Litigation

    Some commercial cases involve securities litigation, particularly when disputes arise from investments, securities transactions, alleged misrepresentations, or violations of securities laws.

    These situations often involve sophisticated legal and financial issues requiring careful analysis of the underlying transactions.

    Fraud Claims and Unfair Competition

    Businesses sometimes pursue fraud claims when they believe another party made false statements, concealed important facts, or engaged in deceptive practices during business negotiations or commercial transactions.

    Similarly, allegations of unfair competition may arise when a competitor engages in conduct that unlawfully interferes with another company’s business operations or market position.

    These claims often depend on the available evidence and whether the law recognizes the alleged conduct as actionable.

    Non-Compete Agreements

    Disputes involving non-compete agreements frequently arise when a former employee or business associate begins working for a competitor or starts a competing business.

    Depending on the facts, litigation may focus on whether the agreement is enforceable, whether it was violated, and what remedies may be available under Virginia law.

    How Does the Commercial Litigation Process Work?

    Although each case is different, the litigation process follows a series of steps designed to identify the issues, gather evidence, and resolve the dispute. Commercial litigation may take several months or several years depending on the complexity of the dispute, the amount of evidence, court scheduling, and whether the case settles before trial.

    Initial Investigation and Case Evaluation

    Before filing a lawsuit, attorneys typically conduct due diligence by reviewing contracts, correspondence, financial records, and other relevant documents.

    They also evaluate the available evidence, applicable law, possible legal defenses, and the client’s objectives before recommending a course of action.

    Filing Pleadings

    If litigation becomes necessary, the plaintiff files a complaint explaining the legal claims against the defendant. The defendant then has an opportunity to respond by filing an answer and raising any applicable defenses. These pleadings establish the issues that will be addressed throughout the case.

    What Happens During Discovery?

    After the pleadings are filed, the case enters the discovery process, which is often one of the longest phases of commercial litigation.

    During discovery, each side gathers information to evaluate the claims and defenses. Depending on the case, discovery may include:

    • Exchanging relevant documents
    • Answering written questions (interrogatories)
    • Taking depositions of parties and witnesses
    • Obtaining expert opinions when appropriate

    The goal is to allow both parties to understand the evidence before trial. In many commercial cases, the information uncovered during discovery influences settlement discussions and directs the remainder of the litigation process.

    After discovery, the parties may file motions asking the court to resolve legal issues before trial. Depending on the circumstances, these motions can narrow the issues, resolve certain claims, or determine whether the case proceeds to trial.

    If the dispute is not resolved through settlement, mediation, or arbitration, the case proceeds to trial, where each side presents evidence, examines witnesses, and makes legal arguments before a judge or, in some cases, a jury.

    Can Commercial Disputes Be Resolved Without Going to Trial?

    Although commercial litigation involves the possibility of a trial, many commercial disputes are resolved before a judge or jury reaches a decision.

    Several forms of alternative dispute resolution may help the parties settle disagreements while avoiding the time and expense associated with lengthy court proceedings.

    Mediation

    Mediation is one of the most common alternative dispute resolution methods used in commercial litigation.

    A neutral third party, known as the mediator, works with both sides to facilitate discussions and explore possible settlement options. Unlike a judge or arbitrator, the mediator does not decide who wins the case or issue a ruling.

    If both sides reach an agreement and each party agrees to the proposed resolution, the dispute may conclude without proceeding to trial.

    Arbitration

    Arbitration is another form of alternative dispute resolution that is often required by contract. In arbitration, a neutral third party hears evidence and legal arguments before issuing a binding decision if the parties agreed to binding arbitration. Depending on the agreement and applicable law, arbitration may provide a different path for resolving disputes than traditional litigation.

    Whether mediation or arbitration is appropriate depends on the contract terms, the legal issues involved, and the goals of the parties.

    What Remedies May Be Available in Commercial Litigation?

    The appropriate remedy depends on the nature of the commercial dispute, the evidence presented, the governing contract, and state law.

    Possible remedies may include:

    • Monetary damages to compensate for proven financial harm or losses incurred
    • Specific performance, requiring a party to fulfill contractual obligations when monetary compensation is inadequate
    • Injunctive relief to stop certain conduct
    • Declaratory judgments that establish the parties’ legal rights and obligations
    • Other remedies authorized by law or the parties’ agreement

    The facts of the case, the applicable law, and the evidence presented determine what relief, if any, may be appropriate.

    When Should You Contact a Commercial Litigation Attorney?

    Not every business dispute requires filing a lawsuit, but waiting too long can limit your options or allow problems to become more difficult to resolve.

    Speaking with a Northern Virginia commercial litigation attorney early in the process can help you understand your legal position before a disagreement grows into a larger conflict. Whether you’re reviewing a potential contract breach, responding to allegations of fraud, addressing shareholder disputes, or evaluating business torts, obtaining legal counsel early may help preserve important evidence and identify practical solutions.

    A commercial litigation attorney helps clients understand the strengths and weaknesses of their position, identify available legal defenses, evaluate the possible consequences of different approaches, and develop a strategy that aligns with their business objectives. In some situations, early legal guidance may also help resolve a dispute before litigation becomes necessary, while preparing a strong strategy if court proceedings cannot be avoided.

    Frequently Asked Questions

    What is commercial litigation?

    Commercial litigation is the legal process used to resolve business disputes involving contracts, partnerships, corporations, commercial transactions, and other business-related legal issues through negotiation, alternative dispute resolution, or court proceedings.

    Is commercial litigation the same as business litigation?

    The terms are often used interchangeably. Both terms involve legal disputes arising from business activities, although the exact terminology may vary depending on the context.

    What is the most common type of commercial litigation?

    A breach of contract is among the most common reasons businesses become involved in commercial litigation, but cases may also involve fraud, partnership disagreements, shareholder conflicts, business torts, or intellectual property disputes.

    Do all commercial litigation cases go to trial?

    Many commercial disputes are resolved through negotiation, mediation, arbitration, or settlement before reaching trial.

    How long does commercial litigation take?

    The timeline varies depending on the complexity of the dispute, the number of parties involved, the amount of evidence, court scheduling, and whether the matter settles before trial. While every case is different, commercial litigation can take anywhere from several months to several years to resolve.

    What is the discovery process?

    The discovery process is the stage of litigation during which the parties exchange information, produce relevant documents, answer written questions, and gather evidence to support their claims or defenses.

    What remedies are available in commercial litigation?

    Depending on the circumstances, remedies may include monetary damages, specific performance, injunctions, declaratory judgments, or other relief available under Virginia law.

    What is specific performance?

    Specific performance is a court order requiring a party to fulfill obligations under a contract rather than simply paying monetary compensation. Courts reserve it for situations where financial damages alone would not adequately address the harm.

    What should I bring to an initial consultation with a commercial litigation attorney?

    Helpful materials may include contracts, emails, financial records, correspondence, corporate documents, and any other records related to the dispute. Providing complete information allows your attorney to better evaluate the circumstances.

    When should I contact a commercial litigation attorney?

    If a disagreement involving your business cannot be resolved through normal business discussions, or you receive notice of a potential legal claim, consulting a commercial litigation attorney promptly can help you understand your rights, evaluate available options, and determine the most appropriate next steps.

    Protect Your Business Interests With Guidance From PJI Law’s Northern Virginia Commercial Litigation Attorneys

    Business disputes can disrupt operations, strain valuable business relationships, and create uncertainty about the future of your company. Whether you’re facing a breach of contract, shareholder disputes, partnership disputes, business torts, or another commercial dispute, having experienced legal guidance can help you evaluate your options and pursue a strategy that aligns with your business objectives.

    The Northern Virginia commercial litigation attorneys at PJI Law, PLC represent individuals and businesses in a broad spectrum of commercial disputes. From negotiating resolutions outside the courtroom to representing clients throughout complex litigation, our attorneys provide personalized attention, strategic counsel, and aggressive advocacy tailored to the unique circumstances of each case. 

    Our attorneys recognize that successful commercial litigation requires more than legal knowledge. It also requires understanding each client’s business objectives, industry, and long-term goals so legal strategies support practical business decisions whenever possible.

    If your business is involved in a commercial dispute or you need guidance regarding potential legal action, call (703) 865-6100 or contact us online to schedule your consultation today.

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    3900 Jermantown Road, 2nd Floor
    Fairfax, VA 22030
    (703) 865-6100
    https://www.pjilaw.com
  • Your Parent Died and You’re Appointed as the Executor. What’s Next as an Executor of a Will in Richmond, VA?

    Your Parent Died and You’re Appointed as the Executor. What’s Next as an Executor of a Will in Richmond, VA?

    Losing a parent is one of life’s most difficult experiences. While you’re trying to process your loss, family members may already be asking questions, bills still need attention, and legal responsibilities can begin piling up. If you’ve been named the executor of your parent’s will, you’re now responsible for guiding your parent’s estate through Virginia’s probate process. If you’ve never served in this role before, it’s normal to wonder where to begin.

    Fortunately, you don’t have to figure everything out at once. The probate process in Virginia follows a structured path, and understanding what comes first can help you avoid common mistakes while moving the estate forward. Taking one step at a time often makes the responsibilities ahead feel much more manageable.

    Knowing what to expect can make a difficult time a little less overwhelming. From qualifying with the probate court to paying debts, communicating with beneficiaries, and distributing estate assets, understanding your responsibilities as the executor of a will can help you administer your parent’s estate with confidence during this difficult time.
     
    At a Glance

    At a Glance

    • Before you have legal authority to administer the estate, you’ll generally need to qualify with the Clerk of the Circuit Court where your parent lived.
    • You’ll need to gather important documents, protect estate assets, provide required notice to heirs and beneficiaries, and address creditor claims as part of the probate process.
    • As executor, you’ll have a fiduciary duty to protect the estate, follow the terms of the will and Virginia law, and keep careful financial records.
    • Before you can distribute estate assets, you must pay valid estate debts, taxes, and administration expenses.
    • Many estates can be settled in less than a year, although more complex estates may take longer.
    • An experienced estate administration attorney can help if questions arise during estate administration or if disputes develop.

    First, Take a Breath: You Don’t Have to Make Every Decision Today

    When a parent dies, it’s natural to feel pressure to start handling paperwork immediately. Family members may ask questions about inheritances, creditors may begin contacting the family, and financial institutions may request documentation before discussing accounts. While there are important deadlines, very few decisions need to be made within the first few hours or even the first few days.

    One of the biggest mistakes a named executor can make is rushing to distribute property or close accounts before understanding the legal process. Until you’ve officially qualified through the court, your authority to act on behalf of the deceased person’s estate is limited.

    Instead of trying to solve every issue at once, focus on taking the next appropriate step. The probate process in Virginia is designed to move through each stage in order, giving you time to gather information before making major decisions.

    Have you been named the Executor of a will in Richmond, Virginia_

    Your Decisions During the First Week

    The days immediately following your parent’s death often involve practical matters that have little to do with formal executor authority. These are things you can start on right away, before you’ve gone through the court process that gives you legal authority over the estate, covered in the next section.

    Obtain Multiple Certified Copies of the Death Certificate

    Nearly every organization you’ll work with, including banks, life insurance companies, government agencies, investment firms, and financial institutions, will request a certified death certificate before releasing information or transferring ownership.

    Make sure the copies you order have the official raised or embossed seal, since some institutions won’t accept plain photocopies or uncertified printouts. Ordering multiple certified copies upfront can save time later.

    Locate the Original Will and Other Important Documents

    If your parent left a valid will, locate the original signed document rather than relying on copies whenever possible. You’ll also want to gather documents related to:

    • Bank accounts
    • Brokerage accounts
    • Retirement plans
    • Investment accounts
    • Real estate
    • Vehicle titles
    • Insurance policies
    • Business records
    • Recent tax returns
    • Outstanding bills

    Having these records available early can make the probate process much smoother.

    Secure Your Parent’s Home and Belongings

    If your parent owned a home, vehicle, or other valuable personal property, take reasonable steps to secure it. That may include changing locks if necessary, forwarding mail, maintaining insurance coverage, or arranging for ongoing maintenance until ownership is transferred. You don’t need to begin distributing belongings right away. Instead, focus on preserving the property’s value for everyone with an interest in the estate.

    Under Virginia Code § 64.2-511, Virginia law also allows a named executor to take a narrow set of actions even before qualifying with the court: arranging burial, paying reasonable funeral expenses, and taking steps to preserve the estate from waste. Beyond that, most of what you handle in the first week falls to you as a family member helping out, not as the legally authorized executor. That authority comes next.

    Qualifying as the Executor

    You might assume you’re automatically authorized to act as soon as your parent passes away, but that’s not the case. Virginia requires most executors to complete a court process before receiving official authority over the estate.

    One note on terminology: Virginia law and many court forms use the broader term “personal representative.” An executor is a personal representative named in a will, so you’ll often see both terms used throughout the probate process. Since your parent left a will naming you for this role, you’re serving as the executor while also acting as the estate’s personal representative.

    Acting on behalf of the estate covers things like opening an estate bank account, accessing your parent’s financial accounts, paying bills from estate funds, selling or transferring property, and dealing with creditors and financial institutions on the estate’s behalf. Until you’ve qualified, you generally can’t do any of this. That authority only takes effect once the court confirms you as executor.

    How to Qualify in Richmond

    In Richmond, probate and qualification are generally handled before the Clerk of the Circuit Court serving the locality where the deceased person lived at the time of death. To qualify, you’ll generally present the original will, a certified death certificate, required probate forms, and any additional documentation requested by the Clerk of Court.

    Once you’ve qualified, the Clerk of the Circuit Court issues a Certificate of Qualification (also referred to as a letter of administration) that serves as official proof of your authority to act on behalf of the decedent’s estate. Financial institutions and others often request this certificate before allowing you to access estate accounts, transfer assets, or conduct other business on the estate’s behalf.

    What to Know About the Bond Requirement

    A bond is a financial guarantee that helps protect the estate and its beneficiaries if an executor fails to carry out their legal responsibilities properly.

    As part of qualifying, Virginia law requires an executor to provide a bond. The Clerk of the Circuit Court determines the amount of the bond and whether additional security is required under Virginia law. In some instances, the bond may be waived. 

    Can You Decline to Serve as Executor?

    Being named as the executor in your parent’s will doesn’t require you to accept the role. If you don’t wish to serve, you may decline the appointment before qualifying with the Clerk of the Circuit Court. If the will names an alternate executor, that person may qualify instead. Otherwise, the court may appoint another qualified personal representative to administer the estate.

    After You Qualify: What Comes Next?

    After qualification, the probate process officially begins, and several important deadlines start running. One of your first responsibilities is notifying the appropriate people that probate has been opened.

    Under Virginia Code § 64.2-508, the executor must provide written notice to heirs and beneficiaries within 30 days after qualification. You may also need to notify creditors so they have an opportunity to present valid claims against the estate.

    At this stage, you’re acting on behalf of the estate, not yourself or any individual beneficiary. That means decisions should be based on your legal responsibilities rather than family expectations or personal preferences.

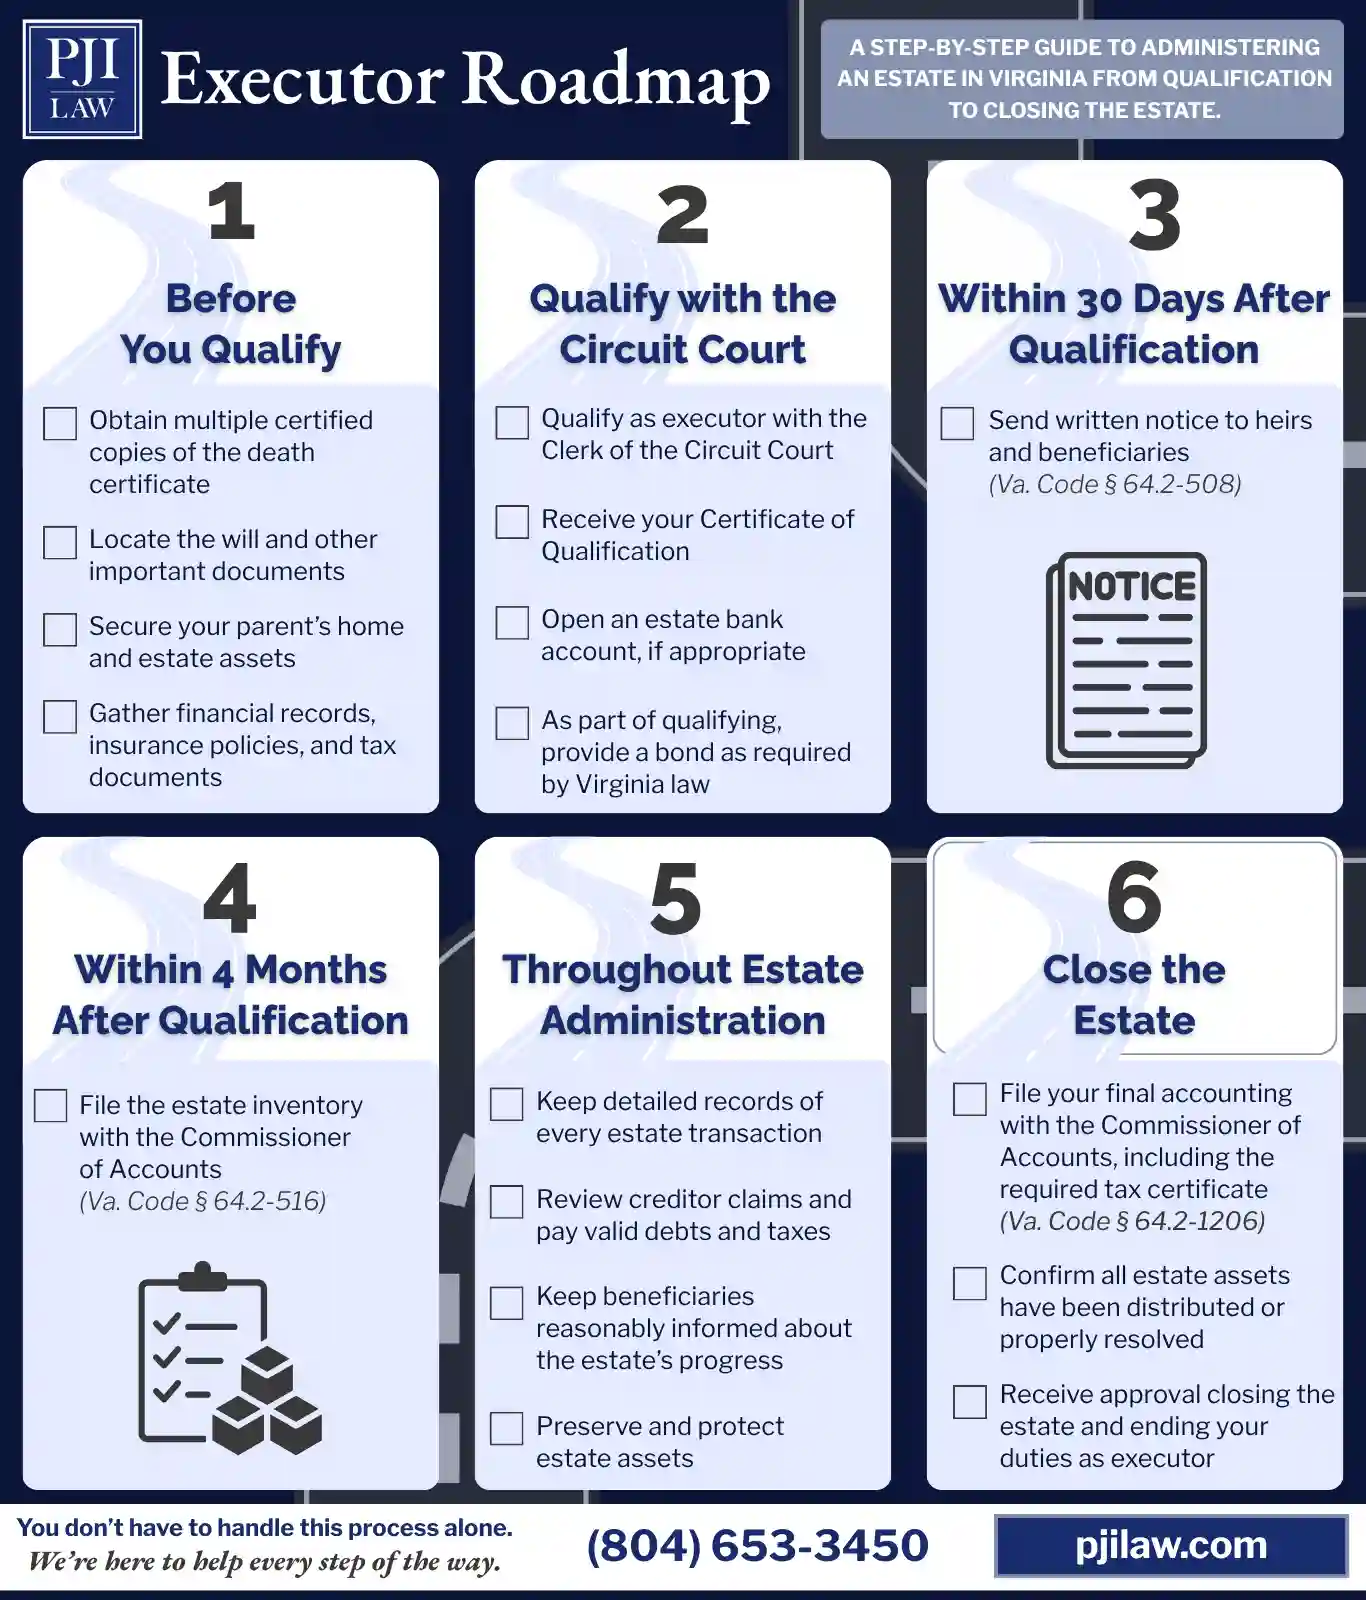
    Executor Roadmap

    Protecting the Estate

    One misconception is that an estate executor simply distributes inheritances. In reality, your first responsibility is protecting the estate until it can be properly administered. Once you’re qualified, protecting the estate becomes a formal legal responsibility, not just the practical steps you may have already taken to secure your parent’s home and belongings.

    Virginia law imposes a fiduciary duty on every executor. A fiduciary duty means you must act honestly, carefully, and in the interests of the beneficiaries while following the terms of the will and applicable state law.

    As the executor, you’re responsible for protecting the decedent’s assets, maintaining accurate financial records, and making decisions that benefit the estate rather than yourself. That duty continues throughout the entire probate process, and two habits will carry you through most of it: keeping estate money separate from your own, and keeping a clear record of everything you do.

    Separate Estate Funds From Your Own

    One of the simplest ways to avoid problems is keeping estate funds completely separate from your personal finances. Many executors open an estate checking account after receiving a federal tax identification number for the estate. Using that account to pay bills and deposit estate income creates a clear record of every transaction.

    Mixing personal and estate money, even temporarily, can create unnecessary complications and, in some situations, expose an executor to personal liability.

    Keep Detailed Records

    Good recordkeeping protects both the estate and you. Maintain documentation of every deposit, every payment, receipts, bank statements, property sales, communications with beneficiaries, professional invoices, and court filings. Keeping careful records makes preparing required reports much easier if questions arise later.

    Identifying Estate Assets

     
    Identifying Estate Assets

    Before property can be transferred to beneficiaries, you’ll need to determine exactly what your parent owned and whether those assets pass through probate. This process often takes longer than many families expect.

    You may need to locate:

    • Checking and savings accounts
    • Financial accounts
    • Retirement accounts
    • Investment accounts
    • Brokerage accounts
    • Real estate
    • Vehicles
    • Business interests
    • Valuable collectibles
    • Jewelry
    • Household items
    • Digital assets

    Not every asset becomes part of the probate estate. For example, many jointly owned assets, payable-on-death accounts, retirement accounts with designated beneficiaries, and certain trust assets may pass directly to the intended recipient without going through probate.

    Identifying which assets are probate assets and which transfer outside probate is an important part of estate administration.

    Preparing an Estate Inventory

    Virginia requires executors to prepare an estate inventory identifying probate property and its value. For many assets, you’ll need to determine the fair market value as of the date of death. Depending on the type of property involved, that may require bank statements, investment statements, tax assessments, vehicle valuation guides, or a professional appraiser for real estate, antiques, artwork, or other unique property.

    Under Virginia Code § 64.2-1300, this inventory must be filed with the local Commissioner of Accounts within four months after qualification. Preparing a thorough inventory helps establish transparency throughout the probate process and creates a clear record of the assets under your responsibility.

    Paying Bills Doesn’t Mean Paying Every Bill Immediately

    One of the most common questions executors ask is whether they should begin paying bills as soon as they arrive. As the person responsible for administering the deceased person’s estate, you’re expected to identify valid claims, determine available estate resources, and follow Virginia law regarding the payment of creditors. Paying bills too quickly, or in the wrong order, can create unnecessary complications if the estate doesn’t have enough assets to satisfy every obligation.

    Before making payments, you’ll typically need to identify:

    • Outstanding debts
    • Mortgage payments
    • Credit card balances
    • Medical bills
    • Funeral expenses
    • Utility bills
    • Insurance premiums
    • Other ongoing expenses

    Some expenses should continue during estate administration, particularly if they’re necessary to preserve estate assets, such as homeowners insurance, utilities for an occupied home, or property maintenance.

    At the same time, you’ll also need to review creditor claims carefully. Not every debt presented to the estate is necessarily valid or enforceable. Because every estate is different, it’s often wise to understand your responsibilities before making large payments from estate funds.

    Taxes Are Still Part of Your Responsibilities

    Serving as an executor also means handling several tax-related obligations before you can distribute assets. Depending on the circumstances, you may need to file the decedent’s final income tax return, fiduciary income tax return(s) for the estate, any remaining federal or state tax returns, and an estate tax return, if required under applicable tax laws.

    Not every estate will owe estate tax, but determining whether any filing requirements apply is still part of the administration process. If the estate earns income after your parent passes away, for example through rental property, dividends, or investment earnings, you may also need to report that income appropriately.

    Because tax matters can become complicated, many executors work with a tax accountant or other qualified professional, particularly when an estate includes rental property, a business interest, or a sizable investment portfolio.

    Keep Beneficiaries Informed Throughout the Probate Process

     
    Keep Beneficiaries Informed Throughout the Probate Process

    Grief and uncertainty make people anxious for answers, and many probate disputes begin simply because someone feels left in the dark. Even when you’re following the law, a lack of communication can create unnecessary tension among beneficiaries and other interested parties.

    As executor, you’re generally expected to keep beneficiaries reasonably informed about the progress of estate administration. That doesn’t mean providing daily updates. Instead, clear communication about major developments, such as property sales, creditor claims, court filings, or expected distribution timelines, can help reduce misunderstandings.

    If more than one sibling is involved, maintaining transparency also helps demonstrate that you’re fulfilling your fiduciary duty fairly and consistently.

    Avoid These Common Mistakes While Administering an Estate

    Even conscientious executors, doing their best during an already hard time, can run into trouble if they’re unfamiliar with the probate process. Some of the most common mistakes include the following.

    Distributing Property Too Soon

    It can be tempting to begin dividing family heirlooms or transferring remaining property shortly after the funeral. However, you generally shouldn’t distribute estate assets until the estate’s debts, taxes, expenses, and legal obligations have been addressed.

    Mixing Estate and Personal Funds

    Never deposit estate money into your personal bank account or use personal funds without maintaining complete documentation. Keeping separate financial records protects both the estate and you.

    Failing to Document Transactions

    Whether you’re selling a vehicle, paying a contractor, or reimbursing an expense, maintain supporting documentation. Detailed records help explain each financial decision if questions arise later.

    Ignoring Court Deadlines

    Virginia’s probate system includes deadlines for notices, inventories, accountings, and other required filings. Missing those deadlines can delay administration and create additional work.

    Self-Dealing

    An executor cannot use estate property for personal benefit simply because they’re administering the estate.

    For example, purchasing estate property below fair market value, borrowing estate funds, or giving yourself preferential treatment over other beneficiaries may constitute self dealing and expose you to legal challenges.

    Are you seeking guidance after you were appointed as the Executor of your parent’s estate in Richmond, Virginia_

    Can You Be Held Personally Liable?

    Although serving as an executor doesn’t automatically create personal financial responsibility for your parent’s debts, you can be held personally liable if you violate your legal obligations while administering the estate.

    Acting honestly, keeping accurate records, and following Virginia’s probate requirements are what keep most executors free of personal liability. None of that happens automatically, though, and the responsibility to get it right rests with you throughout the process.

    Closing the Estate

    Once all debts, taxes, and expenses have been paid and the remaining assets have been distributed to beneficiaries, the final step is closing the estate with the court.

    Under Virginia Code § 64.2-1206, the executor must account for the estate before the Commissioner of Accounts. The final accounting should show that debts, expenses, and distributions have been accounted for and that the remaining estate assets have been properly distributed or resolved.

    Once the Commissioner of Accounts reviews and approves that final accounting, you’re formally released from your duties as executor, and your legal responsibility for the estate comes to an end.

    How Long Does the Probate Process Usually Take?

    Every estate is different. For relatively simple estates with cooperative beneficiaries, few creditors, and straightforward assets, estate administration may be completed in less than a year.

    More complicated estates often require additional time, particularly when they involve real estate sales, closely held businesses, multiple beneficiaries, will contests, tax issues, difficult creditor claims, or property located in multiple states.

    Virginia also requires executors to comply with statutory timelines for inventories and periodic accountings reviewed by the local Commissioner of Accounts, so the overall timeline depends on both the estate’s complexity and compliance with those requirements. Patience is often one of the most valuable qualities an executor can bring to the process.

    When Should You Consider Working With an Estate Administration or Probate Attorney?

    Virginia doesn’t require every executor to hire an attorney, and many smaller estates proceed smoothly without extensive legal assistance.

    Professional advice tends to matter most when:

    • Family members disagree about the will
    • Someone challenges the estate
    • The estate includes a sizable real estate or business interest
    • Complicated tax issues arise
    • Creditors dispute claims
    • The estate owns a substantial investment portfolio
    • You’re serving as sole executor for a large or complex estate
    • More than one executor is involved and disagreements develop over administration

    Having legal guidance can help you understand your responsibilities while reducing the likelihood of mistakes that delay the probate process or create unnecessary disputes.

    Looking for guidance from an attorney for wills in Richmond, Virginia_

    Frequently Asked Questions

    Can an executor also be a beneficiary?

    It’s common for a named executor to also be an intended beneficiary under the will. Even so, the executor must continue fulfilling their fiduciary duty and treat all beneficiaries fairly.

    Does every estate have to go through the full probate process?

    Under Virginia Code § 64.2-601, Virginia offers a simplified affidavit process for smaller estates where the decedent’s personal probate estate doesn’t exceed $75,000, not counting real estate. If the estate qualifies, some assets may be collected without going through formal probate at all. An attorney can help you determine whether your parent’s estate meets the requirements.

    Can I refuse to serve as executor?

    If you don’t wish to serve, you may generally decline the appointment. If the will names an alternate executor, that person may serve instead. Otherwise, the court can appoint another qualified personal representative.

    Can an executor change the terms of the will?

    An executor must administer the estate according to the will and applicable state law. They cannot rewrite or modify the deceased person’s wishes.

    What happens if my other parent is still alive?

    A surviving spouse has independent rights under Virginia law, regardless of what the will says. These include a family allowance, an exempt property allowance, and a homestead allowance, along with the option to claim an elective share of the estate instead of what the will provides. These claims are paid before most creditors and before other heirs, and the surviving spouse generally has up to a year after the death to make them. If your other parent is still living, part of your role as executor is understanding how these rights may affect what’s ultimately available to distribute to everyone else.

    Do all assets go through probate?

    Certain trust assets, jointly owned property, and accounts with beneficiary designations may transfer outside the probate process.

    Can I sell my parent’s house?

    Whether you have authority to sell real estate depends on the terms of the will, Virginia law, and, in some situations, whether court approval is required.

    Will I need to open an estate bank account?

    Often, yes. Opening a separate account helps manage estate funds, pay expenses, and maintain accurate financial records throughout administration.

    Can family members demand their inheritance immediately?

    Before you can distribute assets, you must complete required probate procedures, resolve creditor claims, pay taxes and expenses, and determine what remaining assets are available for distribution.

    What if I have questions during the probate process?

    Every estate presents different challenges. If questions arise about your responsibilities, deadlines, taxes, or potential liability, speaking with an experienced estate administration attorney early in the process may help prevent larger issues later.

    Move Forward With Confidence as You Administer Your Parent’s Estate

    Serving as an executor often comes at one of the most difficult times in your life. While you’re coping with the loss of a parent, you’re also expected to manage court filings, financial matters, communication with beneficiaries, and the legal responsibilities that come with being an executor of a will. You don’t have to handle every challenge on your own.

    At PJI Law, PLC, our Richmond, Virginia, estate administration and probate attorneys help clients understand executor responsibilities, comply with Virginia probate requirements, and move through estate administration with confidence. Whether you’re administering a straightforward estate or facing family disagreements, tax questions, or complex assets, we’re here to provide practical guidance tailored to your situation.

    Call (804) 653-3450 to schedule your complimentary consultation. You can also complete our confidential online form if that’s more convenient.

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    4108 E Parham Road
    Richmond, VA 23228
    (804) 653-3450
    https://www.pjilaw.com/

  • Are Text Messages Admissible in Civil Court in Virginia, Alongside Emails and Social Media?

    Are Text Messages Admissible in Civil Court in Virginia, Alongside Emails and Social Media?

    That text message sitting in your phone from three months ago might end up read aloud in a courtroom. So might the email you sent during a contract dispute, or a photo posted the same week something happened between you and a business partner. Maybe you’re on one side of a deal that fell apart and you’re wondering if your texts back it up. Maybe you’re on the other side, and you just realized a message you sent could get used against you instead.

    Once a disagreement turns into a real dispute, you want a straight answer: are text messages admissible in civil court in Virginia? What about the email chain, or a photo you posted?

    Often, yes, on all three. But existing on your phone and getting admitted in front of a judge are two different things. Text messages, emails, and social media posts all have to clear the same hurdles as any other evidence before a court takes them seriously.

    Knowing what those hurdles are and acting on them now can determine whether a message strengthens your case or never reaches the courtroom.

    At a Glance

    At a Glance

    • Text messages, emails, and social media posts can be admitted in Virginia civil court if they satisfy the Virginia Rules of Evidence.
    • Courts look at whether the evidence is relevant, authentic, and free of other evidentiary problems.
    • Text messages often need extra proof showing who actually sent them and whether they’ve been altered.
    • Deleting a message doesn’t always mean it’s gone. Recovery is sometimes possible through lawful means.
    • Preserving digital communication early cuts down on authenticity disputes later.

    Are Text Messages Admissible in Civil Court in Virginia?

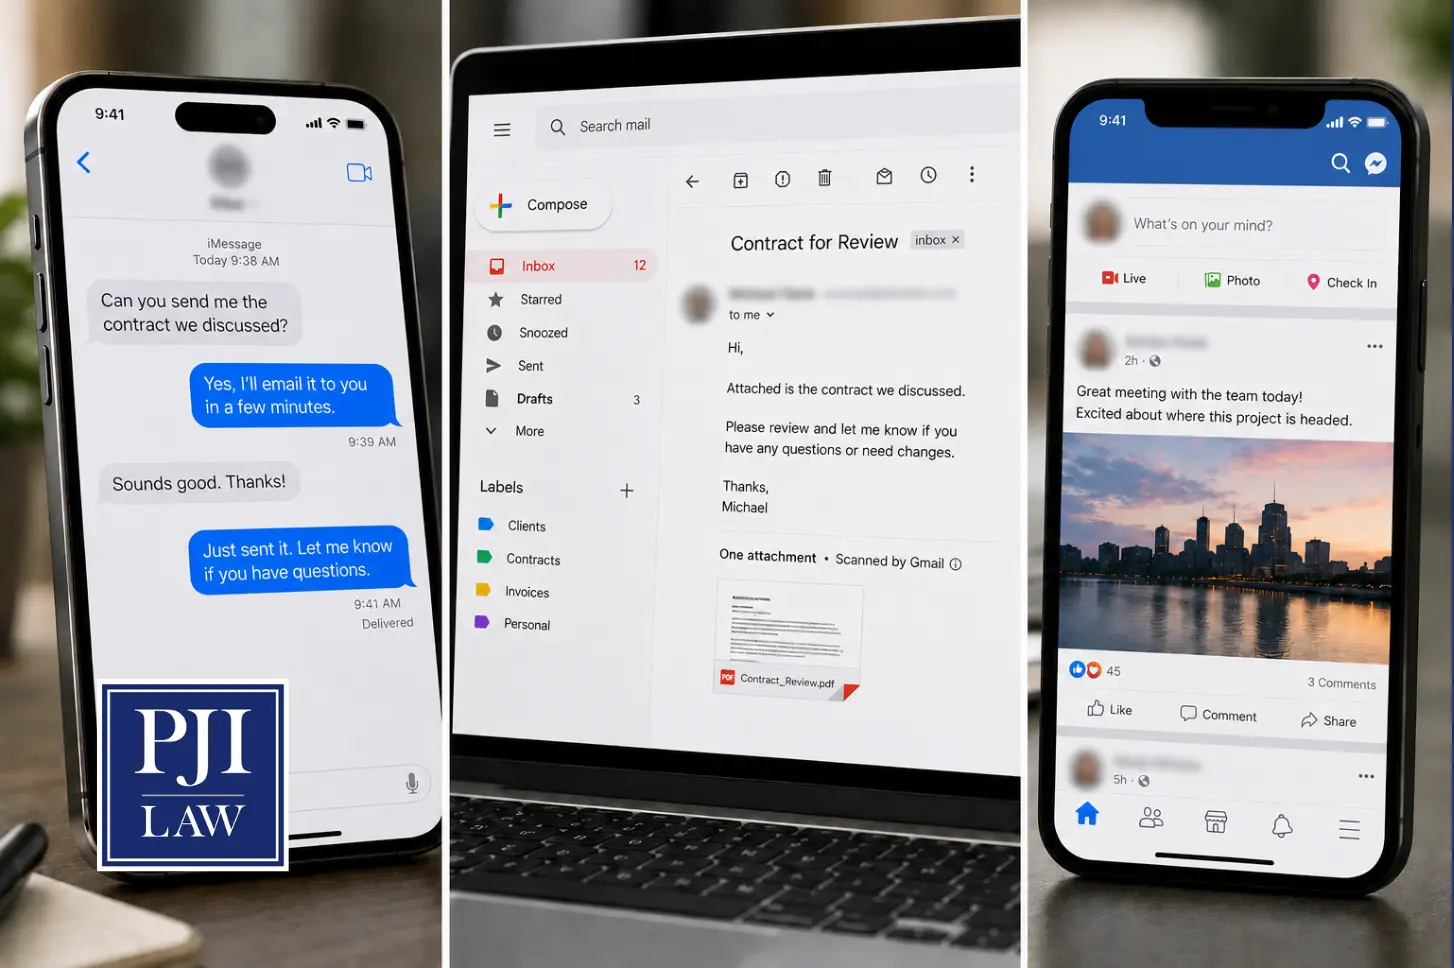
    In many cases, text messages are admissible in Virginia civil court if they satisfy the applicable Virginia Rules of Evidence. A text message isn’t automatically accepted the moment someone offers it during litigation, any more than a photograph or a document would be.

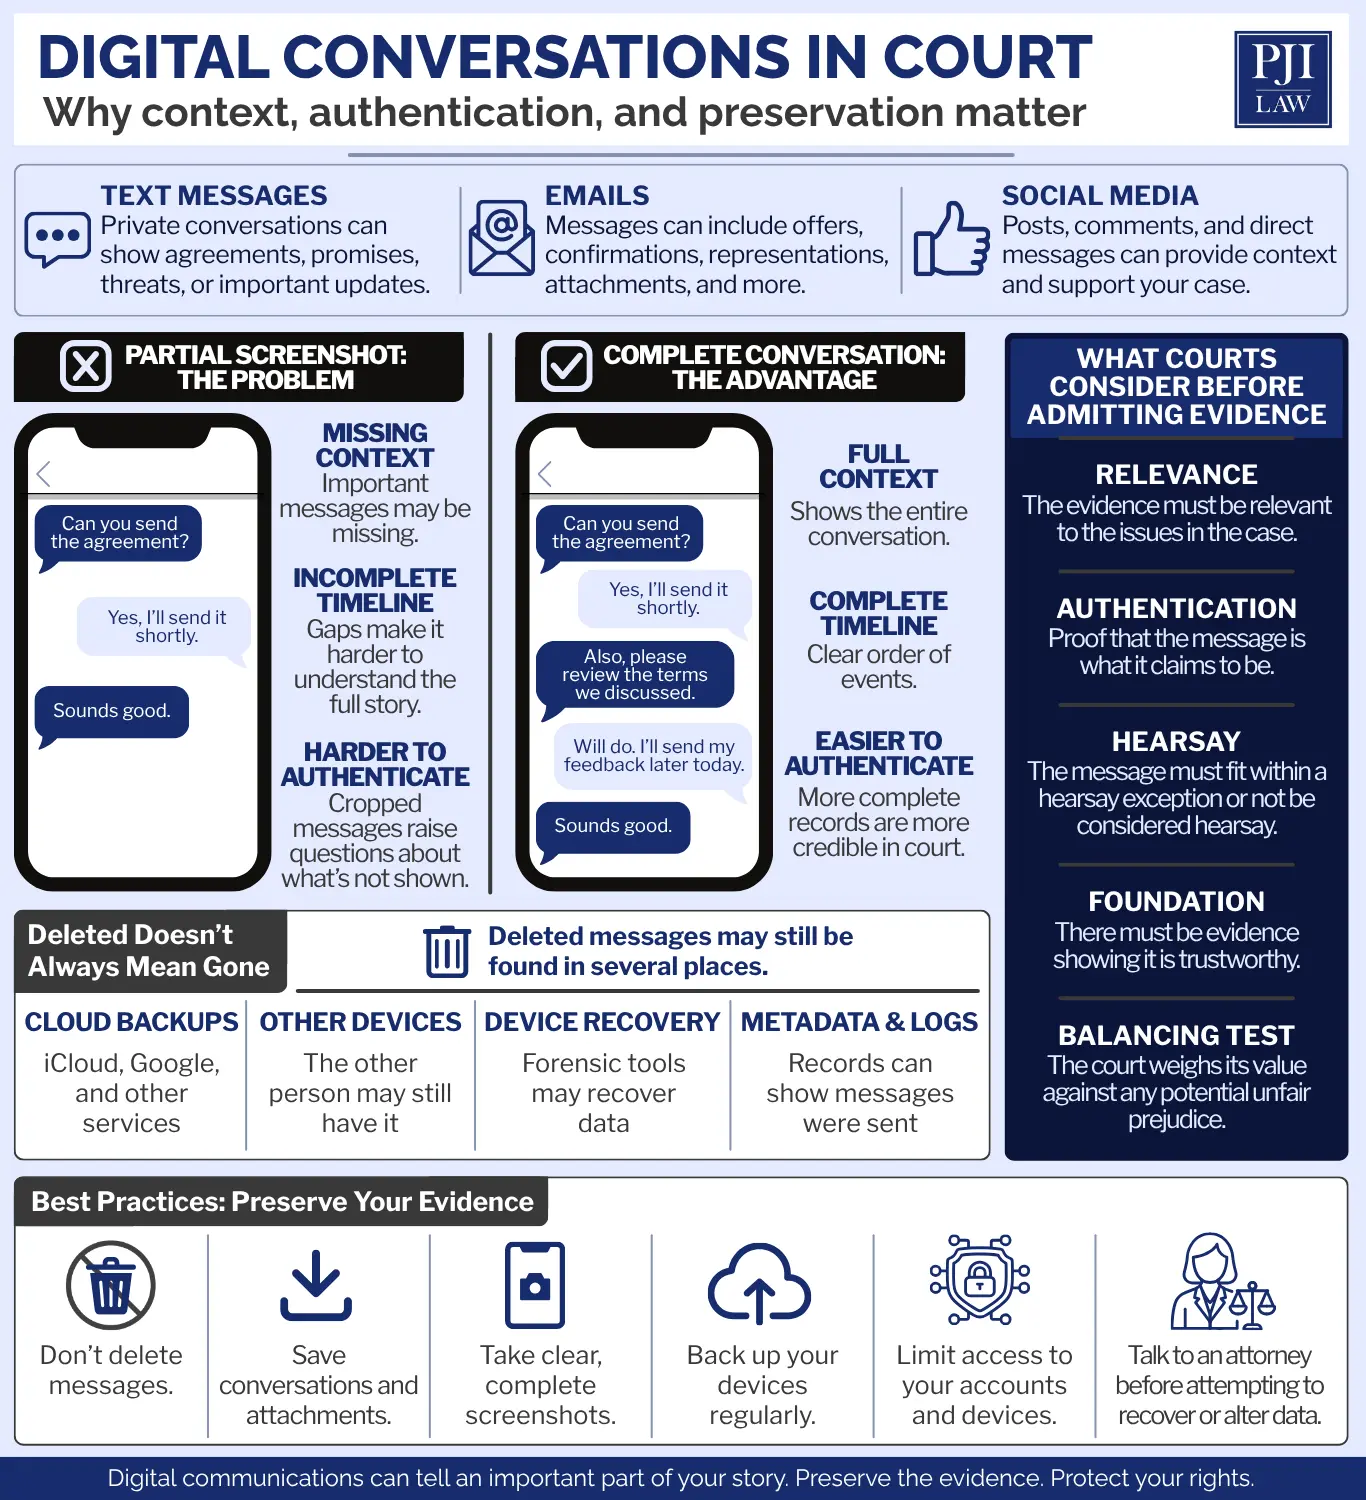
    Before a judge allows a text message to be admitted as evidence, the court considers whether it’s relevant to the issues in dispute, properly authenticated, admissible under the Virginia Rules of Evidence, and presented in full rather than cherry-picked out of context.

    That last point trips people up more than they expect. A single text can prove an agreement existed, pin down a timeline, or reveal what someone knew and when. It can also mean almost nothing on its own until it’s placed next to other evidence in the case. Courts increasingly treat text messages as evidence alongside emails and social media, part of one connected web of digital communication rather than isolated pieces.

    Seeking a civil litigation attorney to prove your case involving text messaging or direct messages in Virginia

    Sending a Message Doesn’t Keep It Private

    A lot of people assume a private message stays private unless somebody breaks the law to get it. Once you send a text, email, or direct message to another person, you’ve given up control over what they do with it. If they take a screenshot, forward it, or show it to their attorney, that’s not a privacy violation on their part.

    The message is theirs to keep and share once it lands in their inbox or on their phone. That’s part of why so many people find themselves surprised at what turns up in a lawsuit. The conversation felt private in the moment, but legally, it only takes one participant deciding to save it.

    What Actually Makes a Text Message Admissible

    Courts weigh a text message against several distinct requirements before it becomes evidence. Miss one, and it doesn’t come in, however damaging or convincing the content might be.

    It Has to Be Relevant

    If a message doesn’t connect to a fact actually in dispute in the lawsuit, it doesn’t get in, no matter how interesting it is. Relevant messages tend to show up in contract negotiations, real estate transactions, fraud claims, mechanic’s lien disputes, property disagreements, conversations tied to an incident, or outright admissions. The tighter the connection to what’s being disputed, the more weight the message can carry.

    Take a mechanic’s lien dispute as an example. If a contractor texted you photos of completed work and a promise to finish the punch list by a certain date, that exchange speaks directly to what was promised and when. A separate text from the same week about weekend plans, unrelated to the job, wouldn’t clear the relevance bar even though it came from the same conversation.

    It Has to Be Authenticated

    This is where challenges happen more often than anywhere else. A screenshot alone doesn’t prove anything. Before a text message counts as evidence, the person offering it typically has to show it’s genuine, meaning it’s what they claim it to be. Virginia’s authentication requirements are set out in the Code of Virginia, Chapter 14 on Evidence, which several of the Rules of Evidence on authentication and business records are drawn from directly.

    That proof can come from:

    • Testimony from someone who participated in the conversation
    • Testimony from a witness familiar with the messages
    • Information connecting the phone, device, or account to a particular person
    • Metadata showing when the communication occurred
    • Other identifying details that support authenticity

    Say a business partner disputes ever sending an email agreeing to a payment split. Metadata showing the email originated from their account, combined with testimony from someone who saw them draft it, can be enough to establish it’s genuine even without their cooperation.

    Authentication doesn’t require eliminating every possible doubt. It requires enough for the court to reasonably conclude the message is real before deciding how much it’s worth to the case.

    It Has to Be Complete

    A single screenshot rarely tells the whole story. Pull one line out of a longer conversation and it can look damning. Read the full exchange and that same line might read as a joke, a misunderstanding, or something walked back two texts later. Judges tend to favor full conversations over curated excerpts, and original messages over edited screenshots, for exactly this reason.

    Other Rules Can Still Block It

    Even a relevant, authenticated, complete message can run into hearsay objections, privilege issues, unfair prejudice arguments, or other procedural roadblocks. Hearsay and its exceptions, including the exception for business records, are addressed directly in Rule 2:803 of the Virginia Rules of Evidence. One exception worth knowing: Your own texts or emails are generally treated as an admission by a party-opponent, meaning your own words can be used against you without running into a hearsay problem at all.

    A message you send to someone else typically doesn’t get the same hearsay protection a statement made in court would. Judges evaluate these objections based on Virginia law and the specific circumstances surrounding the communication. For that reason, whether a particular text message is admissible often depends on more than simply whether the text message exists.

    Looking for a law firm experienced in guiding clients through the intricacies of admissible evidence for contract cases in Virginia

    What About Emails?

    Emails carry a lot of the same weight as text messages, and in business disputes, contract disagreements, and real estate transactions, they’re often the core of the paper trail. They tend to preserve exactly what courts want to see: timestamps, sender and recipient information, and attachments that document decisions, approvals, financial terms, or changes to an agreement.

    Courts still expect emails to be authenticated the same way texts are. Shared inboxes, forwarded chains, edited content, and missing attachments all raise questions that need answers before an email gets treated as reliable. Save the original whenever you can. A printed copy or a partial excerpt gives the other side more room to argue it’s incomplete or altered.

    What About Social Media?

    Public posts, photos, videos, comments, marketplace messages, location check-ins, and even private direct messages can all become relevant depending on what’s being disputed. Courts don’t treat something differently just because it lives on Instagram instead of in a text thread. The same authentication questions apply: who controlled the account, has anything been deleted or edited, and does other evidence back up what’s being shown.

    Ever posted something you didn’t think twice about, only to realize later it lined up with the exact week your dispute started? That’s where people get caught off guard. A photo posted the same week a property dispute began, or an offhand comment about a business disagreement, can end up carrying more weight than it seemed to at the time.

    What Happens if the Messages Are Already Deleted?

    What Happens if the Messages Are Already Deleted

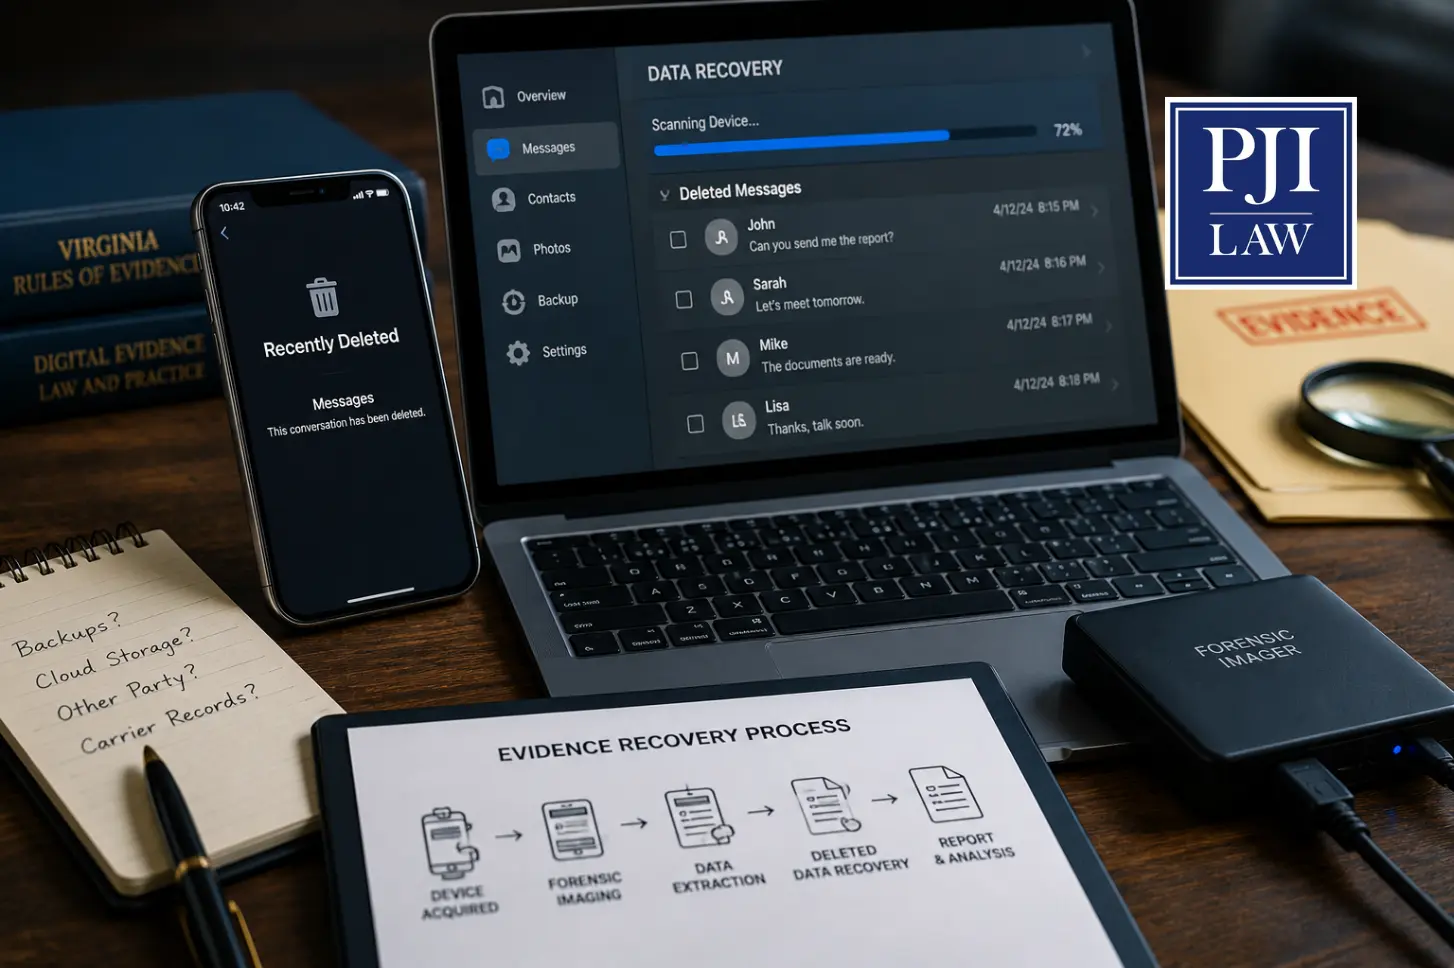
    Deleting a conversation feels final. It often isn’t. Whether a deleted message can be recovered depends on how long ago it happened, whether backups exist, whether the device has kept being used since, whether cloud storage caught a copy, and whether the other person in the conversation still has it on their end.

    In some cases, forensic tools used by trained professionals can pull deleted messages back from a device or backup, though recovery isn’t something you can count on, and time works against you.

    One distinction worth knowing: Phone carriers often keep records showing that a message was sent or received at a certain time, but they typically don’t retain the actual content. If deleted communications could affect your case, talk to a lawyer before you try to recover or alter anything on the device yourself.

    How Would the Other Side Even Get Your Messages?

    Many people assume their texts and private messages are safe unless they choose to hand them over. That’s not how it usually works. In a civil case, the other side has formal ways to request your electronic communications during discovery, the phase where both sides exchange information before trial.

    That typically includes requests for production of documents, which can cover text messages, emails, and social media content stored on your phone, in the cloud, or through the app you used to send them.

    If you don’t produce what’s requested and a court believes you should have, that alone can raise more red flags than the messages themselves. In cases where a subpoena is issued to a third party, like a cell carrier or a platform such as Meta or Google, records tied to your account can be turned over even if you deleted the conversation on your end.

    Protecting Your Digital Evidence Before It’s Gone

    Your biggest mistake won’t be sending the wrong text. It’ll be waiting too long to preserve it. Devices get replaced, accounts get closed, auto-delete settings quietly clear out conversations, and information gets overwritten without anyone deciding to erase it on purpose.

    Ask yourself: If your case went to court tomorrow, could you actually produce the original conversation, or just your memory of it? If your dispute looks like it’s headed toward litigation:

    • Hold onto your original device
    • Save full conversations instead of cropped screenshots
    • Keep emails with their attachments intact
    • Note dates and times
    • Avoid marking up or editing anything
    • Back up what you can

    One warning worth taking seriously: Once litigation has started, or is reasonably expected, deleting relevant evidence isn’t just risky. It can lead to real legal consequences. Courts don’t look kindly on evidence that should have existed and mysteriously doesn’t.

    Do Screenshots Alone Prove Anything?

    Not usually. A screenshot shows a conversation, photo, or post, but on its own it doesn’t establish who created it, whether it’s been altered, or whether it reflects the full exchange. That’s why attorneys often go looking for more: the original messages, metadata, device information, backup records, or testimony from someone who was actually part of the conversation.

    One screenshot standing alone is a weak foundation. The strongest digital evidence tells the complete story, not just part of it.

    This is also why forensic recovery tends to hold up better than a screenshot pulled from someone’s phone. A qualified professional extracting data from a device can document exactly how the information was collected and preserved, creating a clear chain of custody from the original source to the courtroom. A screenshot, by contrast, has no such trail. Anyone could have taken it, edited it, or cropped it before it reached you.

    DIGITAL CONVERSATIONS IN COURT

    How the Other Side Can Push Back on Your Evidence

    Text message evidence gets challenged constantly, and usually along the same lines. The opposing party might argue the messages weren’t actually sent by the person you’re pointing to, that the conversation is incomplete, that a screenshot was altered, that the messages lack context, or that someone else had access to the phone or account at the time.

    Ever left your phone sitting on a table at a bar or an open office? That’s all it takes for someone to argue the messages came from someone else entirely. Beating back these challenges usually comes down to corroborating evidence, credible testimony, and records that were preserved the right way from the start.

    Can Digital Evidence Actually Win Your Case?

    It can carry real weight. Modern lawsuits are full of digital communication, and it often ends up proving the existence of an agreement, pinning down a timeline, showing what someone knew, revealing intent, confirming conversations between the parties, backing up witness testimony, or contradicting a story that’s changed.

    In contract disputes, email chains can lay out exactly how a negotiation unfolded and who agreed to what. In real estate disputes, texts between buyers, sellers, or agents can confirm what was disclosed and when. In fraud cases, a scammer’s messages can become some of the strongest proof of intent to deceive. In mechanic’s lien disputes, texts with a contractor can pin down what work was promised, completed, or left undone.

    It’s worth noting that criminal cases work under different rules entirely, including Fourth Amendment protections that don’t apply here. Virginia civil courts operate under the Virginia Rules of Evidence, and that’s the standard that governs everything above.

    Small Mistakes That Cost People Their Evidence

    Digital evidence is persuasive right up until someone mishandles it. Deleting messages after a dispute starts, editing screenshots before sharing them, failing to hold onto the original device, posting about the lawsuit online, ignoring emails tied to the dispute, assuming deleted messages will always come back, and waiting too long to call a Virginia civil litigation attorney are the mistakes that show up again and again.

    Acting early keeps evidence in its original form and makes questions about authenticity a lot easier to answer later.

    Searching online for a “civil litigation attorney near me”_

    Frequently Asked Questions

    Are text messages admissible in civil court in Virginia?

    If text messages satisfy Virginia’s evidentiary requirements, including authentication and relevance, they can be admitted during a civil lawsuit.

    Can deleted text messages be recovered?

    Sometimes, through backups, another participant’s device, or forensic tools, though recovery depends on the circumstances.

    Are screenshots enough to admit text messages into evidence?

    Not always. Courts may also want the original messages, metadata, witness testimony, or other supporting evidence.

    Can emails be used as evidence in court?

    Yes, when they’re authenticated and comply with the applicable evidentiary rules.

    Can social media posts be used against someone in a lawsuit?

    Public posts, photos, comments, videos, and private messages can all become relevant depending on the facts.

    What is authentication?

    It’s the process of showing that evidence is genuine and is what the person offering it claims it to be.

    Should I delete text messages before filing a lawsuit?

    Deleting potentially relevant evidence once litigation is anticipated can create serious legal problems of its own.

    What if someone claims they didn’t send the messages?

    Courts weigh testimony, metadata, device information, and surrounding circumstances to sort out who actually sent what.

    Are text messages enough to win a civil case on their own?

    Rarely by themselves. Courts typically look at them alongside testimony, documents, and everything else in the case.

    When should I contact a Virginia civil litigation attorney?

    As soon as you think electronic communications could affect your case. Early guidance can protect evidence before it disappears.

    Protect the Digital Evidence That Could Strengthen Your Case

    Electronic evidence in civil litigation often carries real weight, but only when it’s preserved, authenticated, and presented the right way under Virginia law. The steps you take now, before anything is deleted, altered, or lost, are what determine whether that evidence holds up later.

    At PJI Law, PLC, our team represents individuals and businesses throughout Northern Virginia in a wide range of civil litigation matters. Our Virginia civil litigation attorneys can review your electronic communications, walk through how Virginia law applies to your situation, and build a strategy around the evidence you actually have. Call (703) 865-6100 or contact us online to schedule your complimentary consultation today. 

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    3900 Jermantown Road, 2nd Floor
    Fairfax, VA 22030
    (703) 865-6100
    https://www.pjilaw.com
  • Caught in the Middle: Estate Planning for the Sandwich Generation in Virginia

    Caught in the Middle: Estate Planning for the Sandwich Generation in Virginia

    If you’re raising children while helping care for your aging parents, you know what it means to have people depending on you from every direction. Between work, school activities, medical appointments, household responsibilities, and financial obligations, finding time for your own future often falls to the bottom of the list.

    Estate planning for the sandwich generation isn’t just about deciding who inherits your property. It’s about creating a coordinated plan that protects your family, gives trusted people the legal authority to manage your financial affairs if you’re unable to do so, provides for your children, and protects your loved ones from unnecessary complications during a difficult time.

    Whether you’re updating an existing estate plan or creating one for the first time, taking action now can protect the people who rely on you today and in the years ahead.

    At a Glance

    • The sandwich generation refers to adults who support both aging parents and dependent children.
    • Estate planning for the sandwich generation should address both your own needs and the needs of multiple generations.
    • A comprehensive estate planning strategy often includes a will, a revocable living trust, power of attorney documents, and advance medical directives.
    • Incapacity planning is just as important as planning for death because someone may need the legal authority to manage your financial affairs if you’re incapacitated.
    • Naming guardians in your will can provide stability for minor children.
    • Reviewing your parents’ estate planning documents can identify outdated plans before an emergency occurs.
    • Working with an experienced estate planning attorney can help you develop a plan that reflects your family’s unique responsibilities under Virginia law.

    What Is the Sandwich Generation?

    The sandwich generation includes adults who are simultaneously caring for aging parents while raising or financially supporting children. It isn’t defined by age. It’s defined by life circumstances.

    If this sounds familiar, you’re in good company. Millions of Americans are balancing work, raising families, assisting parents with medical appointments, managing household finances, and trying to prepare for their own future, all at the same time. As people live longer and many adults have children later in life, more families are finding themselves in this position.

    Imagine this scenario: It’s a Tuesday afternoon. You’re leaving your daughter’s soccer practice when your mother calls, confused about a medical bill she doesn’t remember receiving. You pull into a parking lot to sort it out, knowing dinner still needs to happen and a work deadline is waiting. Tomorrow might bring a parent-teacher conference, your father’s doctor’s appointment, and another stack of bills to review. For many people, this is what life in the sandwich generation actually looks like—not one overwhelming crisis, but a steady stream of competing responsibilities.

    For many families, these responsibilities develop gradually. A parent may begin asking for assistance with paying bills, attending medical appointments, or managing bank accounts. At the same time, your own children continue to rely on you financially and emotionally. Over time, you may realize you’re coordinating care, managing schedules, and making financial decisions for multiple generations while still trying to protect your own future.

    Because you’re balancing so many responsibilities, it’s easy to postpone your own estate planning. Unfortunately, delaying these conversations can leave your family members facing uncertainty if an unexpected illness, serious injury, or other life event affects your ability to make decisions.

    Estate Planning When You’re Supporting Two Generations

    Many people think estate planning only determines what happens after death, but a well-designed plan does much more.

    If you become temporarily or permanently unable to manage your affairs because of an accident or medical condition, someone needs the legal authority to step in. Without the proper legal documents, your loved ones may need to ask a court to appoint someone to act on your behalf. That process can be time-consuming, expensive, and emotionally difficult.

    At the same time, your own children, spouse, or other family members may still depend on your income, your caregiving, or your day-to-day financial management. A thoughtful estate plan answers important questions before a crisis occurs, including:

    • Who can manage your financial affairs?
    • Who can make healthcare decisions if you’re incapacitated?
    • Who will care for your minor children?
    • How will your assets be managed if something happens to you?
    • How can your loved ones avoid unnecessary delays during the probate process?

    Planning ahead allows your family to focus on one another instead of scrambling to solve legal and financial problems during an already stressful situation.

    None of this requires you to solve everything at once. A few key documents, put in place now, can carry a lot of that weight for you later.

    Estate Planning Documents Every Sandwich Generation Family Should Consider

    Every family’s circumstances are different, but several estate planning documents form the foundation of many Virginia estate plans.

    A Last Will and Testament

    A will remains one of the most important legal documents you can create. Your will allows you to:

    • Name beneficiaries to receive your property
    • Choose an executor to administer your estate
    • Name a guardian for your minor children
    • Provide instructions that reflect your wishes

    If you have young children, naming a guardian is one of the most important decisions you’ll make. Under Virginia Code § 64.2-1701, a parent may appoint a guardian for a minor child’s person and estate directly in a will. Without a valid will, a court ultimately decides who will care for your children based on Virginia law, rather than your personal preferences.

    A Revocable Living Trust

    For many families, a revocable living trust can provide additional flexibility beyond a will alone. Unlike a will, a living trust allows you to place certain assets into the trust during your lifetime while continuing to manage them as the initial trustee. You maintain control of the trust and can modify or revoke it as your circumstances change.

    A revocable living trust may also let your loved ones avoid probate for assets properly transferred into the trust. If you later become incapacitated, your chosen successor trustee can step in to administer the trust according to your instructions without waiting for probate court involvement.

    After your death, the successor trustee continues managing and distributing trust property for your named beneficiary or beneficiaries according to the trust’s terms. For parents balancing the needs of children and aging parents, a living trust can provide continuity during periods of incapacity while simplifying the transfer of assets later.

    Financial Power of Attorney

    A financial power of attorney is one of the most valuable planning tools for the sandwich generation.

    This legal document allows you to appoint an attorney-in-fact, also called an agent, to manage your financial affairs if you’re unable to do so yourself, under the authority of the Uniform Power of Attorney Act.

    Depending on the authority you grant, your agent may be able to:

    • Pay bills
    • Access bank accounts
    • Handle real estate transactions
    • Oversee investments
    • Manage business interests
    • File taxes
    • Handle insurance matters

    Many Virginia estate plans include a durable power of attorney, sometimes called a durable financial power of attorney. Virginia Code § 64.2-1602 defines a power of attorney as durable unless the document states otherwise, meaning it remains effective even if you become incapacitated, and this document allows your loved ones to continue managing your finances without asking a court to appoint a conservator.

    Without a properly executed power of attorney, your family members may have no immediate legal authority to access your accounts or make important financial decisions on your behalf.

    Advance Medical Directives and Medical Powers of Attorney

    While a financial power of attorney protects your finances, medical planning addresses healthcare decisions.

    Virginia allows you to create an Advance Medical Directive under the Health Care Decisions Act, which lets you appoint someone you trust to make medical decisions if you’re unable to communicate your wishes. Many people refer to these appointments as medical powers of attorney because they give your chosen healthcare agent authority to act on your behalf.

    Your Advance Medical Directive can also express your preferences regarding medical treatment, life-prolonging procedures, and end-of-life care.

    Completing these documents before a medical emergency reduces uncertainty and gives your loved ones clear guidance during an emotional time.

    Don’t Overlook Your Aging Parents’ Estate Plan

    If you’re helping care for aging parents, your own estate planning is only part of the picture. Many older adults created wills or other estate planning documents years ago but haven’t updated them to reflect changes in their finances, family, or Virginia law.

    Bringing this up with your parents can feel uncomfortable. You may worry it sounds like you’re rushing them, or overstepping. Framing the conversation around peace of mind, rather than worst-case scenarios, often makes it easier for everyone involved.

    It’s worth encouraging your parents to review whether they have:

    • A current will
    • A durable power of attorney
    • An Advance Medical Directive
    • A revocable living trust, if appropriate
    • Updated beneficiary designations
    • A current list of important financial information and assets

    It’s equally important that these documents are signed while your parents still have the legal capacity to do so. Waiting too long may limit their options and could require future court proceedings to establish legal authority over their financial affairs.

    Protecting Your Children While You Care for Your Parents

    When you’re caring for two generations, it’s easy to focus on today’s responsibilities and postpone conversations about the future. However, your estate plan should continue protecting your own children, even while you’re caring for your parents.

    For parents of minor children, this often includes:

    • Naming guardians in your will
    • Creating a revocable living trust to manage inherited assets
    • Naming a successor trustee to oversee trust administration if necessary
    • Reviewing beneficiary designations on life insurance and retirement accounts
    • Coordinating your plan with your overall financial goals

    Without these documents, important decisions affecting your children could be left to a court or handled in ways that don’t reflect your wishes.

    Why Incapacity Planning Can’t Wait

    Incapacity planning is often the first thing to get pushed aside. With so much competing for your attention, it’s easy to handle the will and the property questions and leave incapacity planning for later.

    A serious illness or injury could leave you temporarily or permanently incapacitated, making it difficult to pay bills, access money, oversee a business, or make healthcare decisions.

    Most people don’t picture this happening to them. But a fall, a stroke, or a serious diagnosis can arrive without warning, and your family will need clear authority to act on your behalf right away, not weeks later after a court proceeding.

    Without the proper documents in place, your loved ones may need to petition a court for authority to act on your behalf through a guardianship or conservatorship proceeding under Virginia Code § 64.2-2000 before they can manage your finances or medical care.

    The power of attorney and Advance Medical Directive carry the most weight for incapacity specifically. Together, they let trusted individuals step in and act on your behalf without court involvement, right when your family needs that authority most.

    Common Estate Planning Mistakes the Sandwich Generation Makes

    Balancing multiple responsibilities often leads people to postpone planning altogether. Unfortunately, delays can create additional challenges for the people you’re trying to protect.

    Some of the most common mistakes include:

    • Assuming your parents’ estate planning documents are already current
    • Failing to update beneficiary designations after major life changes
    • Not creating a power of attorney
    • Overlooking incapacity planning
    • Forgetting to name guardians for minor children
    • Leaving newly acquired property outside your revocable living trust
    • Assuming verbal conversations provide legal authority
    • Waiting until a medical crisis to begin planning

    Reviewing your plan on a regular schedule and after major life events keeps it aligned with your family’s changing needs.

    Frequently Asked Questions

    What is the sandwich generation?

    The sandwich generation refers to adults who are simultaneously caring for aging parents and supporting dependent children or young adult family members. These competing responsibilities often make comprehensive estate planning even more important.

    Why is estate planning for the sandwich generation different?

    Estate planning for the sandwich generation requires a multi-generational approach. Instead of planning only for yourself, you may need to address your own financial future while protecting both your parents and your children.

    Does everyone need a revocable living trust?

    Not necessarily. A revocable living trust can spare many families the probate process, provide continuity during incapacity, and simplify the management of certain assets, but whether it’s appropriate depends on your individual circumstances and goals.

    Why is a power of attorney so important?

    A properly drafted power of attorney gives someone you trust the legal authority to manage your financial affairs if you’re unable to do so yourself. Without one, your loved ones may need to seek authority through the court.

    How often should I update my estate plan?

    You should review your estate plan after major life events such as marriage, divorce, the birth of a child, considerable changes in your finances, the death of a loved one, or changes in Virginia law. Even without major changes, reviewing your documents on a regular basis confirms they still reflect your wishes.

    Can I create a power of attorney for my aging parents?

    A power of attorney must be signed by the person granting the authority while they still have the legal capacity to understand the document. If your parent has already lost capacity, you may need to seek legal authority through the court, depending on the circumstances.

    What is the difference between a revocable living trust and an irrevocable trust?

    A revocable living trust generally allows you to manage and modify the trust during your lifetime. An irrevocable trust typically cannot be changed as easily once it’s created and may offer different planning benefits. The right choice depends on your financial goals, the type of property you own, and your overall estate planning objectives.

    Can a revocable living trust avoid probate in Virginia?

    A properly funded revocable living trust can spare the assets titled in the trust from probate. Because the trust continues after your death, your successor trustee can administer and distribute trust property according to your instructions without those assets passing through the probate process.

    Should I review my beneficiary designations as part of my estate plan?

    Beneficiary designations on life insurance policies, retirement accounts, and certain financial accounts generally control who receives those assets, regardless of what your will says. Reviewing them regularly confirms they still reflect your wishes and coordinates with the rest of your estate plan.

    When should I meet with an estate planning attorney?

    It’s a good idea to speak with an estate planning attorney whenever you experience a significant life change, such as getting married, having children, caring for aging parents, purchasing a home or business, or receiving an inheritance. Even if your circumstances haven’t changed, reviewing your estate planning documents on a regular basis keeps your plan current under Virginia law.

    Create an Estate Plan That Grows With Your Family’s Needs

    Caring for both aging parents and children often means you’re making decisions that affect several generations at once. A thoughtfully prepared estate plan protects your loved ones, provides clear legal authority if you’re ever unable to act, and reduces uncertainty during life’s most difficult moments.

    At PJI Law, PLC, our Virginia estate planning attorneys work with individuals and families to create comprehensive plans that reflect their responsibilities, priorities, and long-term goals. Whether you’re considering a revocable living trust, updating a power of attorney, planning for incapacity, or reviewing existing estate planning documents, we’ll work with you to develop a strategy tailored to your circumstances under Virginia law.

    Schedule your complimentary consultation by calling (703) 865-6100 or completing our confidential online form.

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    3900 Jermantown Rd, 2nd Floor
    Fairfax, VA 22030
    (703) 865-6100
    https://pjibe.webteam.ai/


  • What Are the 4 Elements of Fraudulent Misrepresentation in Contract Law in Virginia?

    What Are the 4 Elements of Fraudulent Misrepresentation in Contract Law in Virginia?

    Signing a contract often requires trust. Whether you’re entering into a business transaction, purchasing property, or negotiating another agreement, you expect the information you’re given to be accurate. When someone intentionally provides false information to persuade you to act, the consequences can be significant.

    Although a fraudulent misrepresentation claim is a separate legal claim from a breach of contract claim, it typically grows out of a contract negotiation or transaction, which is why it carries real weight in contract law. In some circumstances, Virginia law allows an injured party to pursue fraud claims based on fraudulent misrepresentation.

    However, not every inaccurate statement will constitute fraud. Courts require proof of specific elements before a plaintiff can recover damages. Understanding those elements can help you determine whether your situation may involve fraudulent misrepresentation in contract law and whether it may be time to speak with Northern Virginia fraud attorneys about your legal options.

    At a Glance

    • Fraudulent misrepresentation occurs when a party relies on a false statement and suffers harm as a consequence.
    • Virginia courts require proof of several key elements before allowing fraud claims to proceed.
    • The statement must involve a material fact rather than an opinion or prediction about future events.
    • Fraudulent inducement may occur when a person is persuaded to enter a contract based on false information.
    • Actual fraud and constructive fraud involve different legal standards.
    • Available remedies may include compensatory damages, punitive damages, rescission of the contract, or other relief.

    What Is Fraudulent Misrepresentation in Contract Law?

    Fraudulent misrepresentation in contract law occurs when one party makes a false representation of an important fact, intending for another party to rely on it, and that reliance leads to harm.

    For example, a business owner may knowingly provide inaccurate financial information to convince someone to purchase a company. A seller may fail to disclose significant defects in a property while making statements suggesting no problems exist. In these circumstances, the issue may go beyond a simple breach of contract and rise to the level of fraud.

    Virginia courts carefully examine the facts of each case because fraud allegations can have serious legal and financial consequences. A plaintiff must present proof that the defendant’s conduct meets the required legal elements.

    The 4 Elements of Fraudulent Misrepresentation in Virginia

    Fraudulent misrepresentation is often explained through four core elements. While Virginia case law may describe fraud using five or six elements depending on how the courts separate each concept, these four concepts provide a practical framework for understanding what courts generally look for when evaluating fraud claims.

    1. A False Representation of a Material Fact

    The first element requires a false statement involving a material fact. A material fact is information that would influence a reasonable person’s decision-making process. In other words, the information is important enough that it could affect whether someone enters into a contract or business transaction.

    Not every inaccurate statement qualifies. Virginia courts distinguish between statements of fact and statements of opinion.

    For example:

    • “This company generated $2 million in revenue last year” may be a statement of fact.
    • “I think this business will double in value next year” is generally an opinion.

    Similarly, unfulfilled promises about future events do not automatically constitute fraud. Courts often focus on whether the statement concerned a present or existing fact rather than a prediction about what may happen later.

    2. Knowledge That the Statement Was False

    The second element involves knowledge. To establish actual fraud, a plaintiff must show that the defendant knew the statement was false when it was made or acted with reckless disregard for the truth.

    This requirement helps separate fraud from honest mistakes. People can make inaccurate statements without committing fraud. Fraud generally involves conduct that is intentional or knowingly deceptive.

    Evidence showing that a person had access to accurate information but chose to provide false information may help support this element.

    3. Intent to Induce Reliance

    A false statement alone is not enough. The plaintiff must also show that the defendant made the statement with the intent to influence another party’s decision. This concept is often associated with fraudulent inducement. Fraudulent inducement occurs when a person is persuaded to enter a contract because of false information provided during negotiations.

    For example, if a defendant intentionally misrepresents a business’s financial condition to convince a buyer to sign an agreement, a court may determine that the statement was intended to induce reliance. Intent can be difficult to prove directly. For this reason, courts frequently examine surrounding circumstances, communications, and conduct when evaluating allegations of fraud.

    4. Reasonable Reliance That Causes Harm

    The fourth element requires proof that the plaintiff reasonably relied on the false representation and suffered harm because of it. Reasonable reliance means the plaintiff actually relied on the statement and that such reliance was justified under the circumstances.

    Courts may examine factors such as:

    • The relationship between the parties
    • The information available at the time
    • Whether the plaintiff had an opportunity to investigate
    • The sophistication of the parties involved

    If the plaintiff relied on the misrepresentation and suffered financial losses, the court may find that this element has been satisfied. Without reliance and the harm it causes, a fraud claim may fail even if a false statement was made.

    How Fraudulent Misrepresentation Differs From a Breach of Contract

    Many people assume that every broken promise amounts to fraud. That is not necessarily true. The difference between fraud vs. breach of contract comes down to timing and intent. A breach of contract generally occurs when one party fails to perform obligations outlined in an agreement. Fraud, on the other hand, typically involves deception that occurs before or during the formation of the contract.

    The distinction can be important because fraud litigation may allow recovery under legal theories that extend beyond ordinary contract remedies. For example, if a business simply fails to perform under a contract, the dispute may involve breach of contract. However, if the business intentionally misled the other party to secure the agreement in the first place, the facts may support fraud claims in addition to contract-based claims.

    Because these distinctions can be complex, courts frequently analyze whether the alleged misconduct is truly separate from the contractual obligations themselves.

    Actual Fraud vs. Constructive Fraud Under Virginia Law

    Virginia law recognizes both actual fraud and constructive fraud. Actual fraud involves intentional deception. The plaintiff must show that the defendant knowingly made false statements with the intent to mislead another person.

    Constructive fraud differs because it may arise even when there is no intent to deceive. In certain circumstances, a false statement made negligently can create liability if another party reasonably relied on the information and suffered harm.

    The distinction can significantly affect how a case proceeds and the type of proof required. When evaluating allegations of actual fraud or constructive fraud, courts often conduct a detailed investigation of the facts, communications, documents, and circumstances surrounding the transaction.

    What Evidence May Help Support a Fraud Claim?

    Successfully pursuing fraud litigation often requires substantial evidence. Depending on the circumstances, relevant proof may include:

    • Contracts and written agreements
    • Emails and text messages
    • Financial records
    • Marketing materials
    • Internal business documents
    • Witness testimony
    • Corporate records
    • Communications between the parties

    Fraud cases can be challenging because defendants rarely admit they intended to mislead someone. For that reason, attorneys often build cases using documents, timelines, inconsistencies, and other evidence that helps establish intent.

    In many cases, plaintiffs must satisfy a heightened burden of proof by presenting clear and convincing evidence rather than merely showing that their version of events is slightly more likely than not.

    What Remedies May Be Available in a Virginia Fraud Case?

    The remedies available in a fraud case depend on the facts and circumstances involved. Potential remedies may include:

    • Compensatory damages for financial losses
    • Rescission of the contract
    • Recovery of out-of-pocket expenses
    • Punitive damages in appropriate cases, capped at $350,000 under Virginia Code § 8.01-38.1, available only upon clear and convincing evidence of egregious conduct
    • Other relief authorized by Virginia law

    The court will evaluate the evidence, the extent of the losses, and the nature of the defendant’s conduct when determining what remedies may be appropriate.

    Because each case is different, the availability of damages often depends on the specific allegations and supporting proof presented to the court.

    Frequently Asked Questions

    What is fraudulent misrepresentation in contract law?

    Fraudulent misrepresentation occurs when a person makes a false statement about a material fact, another party relies on that statement, and the reliance causes harm.

    What is the difference between actual fraud and constructive fraud?

    Actual fraud involves intentional deception, while constructive fraud may arise from negligent misrepresentations even when there was no intent to deceive.

    What is fraudulent inducement?

    Fraudulent inducement occurs when a person is persuaded to enter into a contract based on false information or misrepresentations.

    What evidence is commonly used to prove fraud?

    Evidence may include contracts, emails, financial records, witness testimony, corporate documents, and other materials showing what was said, what was known, and how the parties acted.

    Can a fraud claim exist alongside a breach of contract claim?

    In some circumstances, yes. Courts may allow both claims when the alleged fraud involves conduct that is separate from the contractual obligations themselves.

    Can a false opinion be considered fraud in Virginia?

    Generally, opinions are not treated the same as statements of fact. However, there may be exceptions when a person presents an opinion as fact or possesses information that makes the statement misleading under the circumstances.

    How long do I have to file a fraud lawsuit in Virginia?

    In Virginia, you have two years from the date you discovered or reasonably should have discovered the fraud to file a lawsuit, under Virginia Code § 8.01-243. Virginia Code § 8.01-249(1) establishes that the discovery rule controls when that two-year clock starts, so the deadline can vary based on when the fraud came to light. Given how much weight the discovery date carries, it’s worth speaking with an attorney as soon as you suspect fraud.

    What does reasonable reliance mean in a fraud case?

    Reasonable reliance means that a person relied on a false statement and that such reliance was justified under the circumstances. Courts often examine the relationship between the parties, the information available, and whether additional investigation would have been expected.

    Can a business be liable for fraudulent misrepresentation?

    Yes. Businesses, corporations, and other entities may be held liable when their representatives make fraudulent statements or engage in conduct that supports a valid fraud claim.

    Can I recover punitive damages in a Virginia fraud case?

    Virginia law caps total punitive damages at $350,000 regardless of how serious the misconduct was, under Virginia Code § 8.01-38.1. Courts require clear and convincing evidence of intentional or egregious conduct before awarding punitive damages, which is a higher bar than the standard used for compensatory damages.

    When Suspected Fraud Puts Your Financial Interests at Risk, Speak With Northern Virginia Fraud Attorneys

    Discovering that you may have entered into a contract based on false information can raise difficult questions. Was it simply a failed business deal, or did someone’s conduct cross the line into fraud? The answer often depends on the specific facts, the available evidence, and how Virginia law applies to your situation.

    The Northern Virginia fraud attorneys at PJI Law, PLC represent individuals and businesses involved in complex fraud litigation, contract disputes, and claims involving fraudulent inducement, actual fraud, and constructive fraud. Our attorneys carefully investigate the circumstances surrounding each matter, evaluate potential claims and defenses, and develop legal strategies tailored to our clients’ goals.

    If you believe misrepresentations played a role in a contract or business transaction, call (703) 865-6100 or contact us online to schedule your consultation today.

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    3900 Jermantown Road, 2nd Floor
    Fairfax, VA 22030
    (703) 865-6100
    https://pjibe.webteam.ai/

  • 7 Mistakes to Avoid When Gifting From an Estate in Richmond, Virginia

    7 Mistakes to Avoid When Gifting From an Estate in Richmond, Virginia

    You want to do the right thing for your family. Maybe you’re thinking about transferring your primary residence to a child, helping a family member now instead of later, or trying to minimize taxes before your estate is passed on.

    On the surface, gifting from an estate sounds simple. You give assets now, reduce your taxable estate, and avoid complications later. But what many people don’t realize is that the wrong decision can create serious tax consequences, affect Medicaid eligibility, or cost your family far more in the long run than they ever gain upfront.

    Before you gift assets, it’s important to understand where things can go wrong and why those mistakes can have consequences years down the road.

    At a Glance

    At a Glance

    • Gifting assets during your lifetime can reduce your taxable estate, but it can also eliminate valuable tax advantages tied to inherited property.
    • The stepped-up basis available after a decedent’s death can significantly reduce capital gains tax compared to gifted property.
    • Gifted property carries a carryover basis, which can increase taxable gain when sold.
    • The annual gift tax exclusion allows limited tax-free transfers, but larger gifts may require a gift tax return.
    • Adding a child to a deed as a joint owner can trigger the same tax and Medicaid issues as a direct gift, while also exposing the property to that child’s creditors.
    • Gifting can impact Medicaid eligibility and trigger penalties under the 5-year look-back rule.
    • Transferring assets too early may lead to loss of control and unintended financial consequences.
    • A gift made without coordinating your broader estate plan can create accidental inequalities among beneficiaries or undercut your existing trust documents.
    • Not all strategies that reduce estate taxes will benefit your family overall.

    Looking for an estate planning law firm in Richmond, Virginia to guide your gifting strategy_

    What Does Gifting From an Estate Actually Mean?

    The phrase “gifting from an estate” can mean a few different things, depending on who’s using it. Some people use it to describe assets distributed after death through a will or a trust. Others are referring to lifetime gifting, transferring assets out of what you own now, while you’re still alive, to reduce the size of your taxable estate or support a family member sooner.

    The risks discussed in this blog involve lifetime gifting, not assets distributed after death through a will or trust. That distinction carries weight because assets transferred during your life are treated very differently for tax purposes than inherited property received after death. What looks like a generous and practical decision today can drastically alter how capital gains tax is calculated later, leaving your loved ones with far less than you intended.

    Why Gifting Assets Can Create Unexpected Problems

    Gifting is often viewed as an easy way to simplify an estate, minimize taxes, and avoid probate. In reality, a single transfer ripples across multiple legal and financial areas.

    You are not just transferring ownership. You are also changing:

    • How cost basis is calculated
    • How future capital gains are taxed
    • Whether the asset qualifies for a stepped-up basis
    • How your future Medicaid eligibility is evaluated
    • Whether you retain any control over your own financial security

    These consequences are rarely obvious when the gift is made. Recognizing where people commonly go wrong before you commit to a transfer can save your family thousands of dollars.

    7 Mistakes to Avoid When Gifting From an Estate

     
    7 Mistakes to Avoid When Gifting From an Estate

    1. Losing the Stepped-Up Basis and Triggering a Larger Capital Gains Tax Bill

    One of the costliest mistakes is giving away highly appreciated assets during your lifetime, and it usually comes down to one overlooked detail: cost basis. When property is inherited after your death, the beneficiary typically receives a stepped-up basis equal to the fair market value of the asset at the time of death.

    This adjustment can wipe out decades of built-up capital gains tax exposure. When you gift that same asset while you’re alive instead, the recipient receives your original cost basis, known as a carryover basis, and that single difference can determine whether your family keeps more of the asset’s value or loses a portion of it to taxes. Understanding the difference between a stepped-up basis vs. carryover basis can fundamentally change your strategy.

    For example, if you purchased a Richmond home decades ago for a low price and it has risen in value, gifting it now means your child inherits your original, low purchase price as their baseline. When they sell it, they will owe capital gains tax on gifted property based on the entire growth from the day you bought it, rather than the day they received it. 

    The tax bill doesn’t simply vanish because an asset was a gift; the liability transfers to your loved ones and can lead to an unnecessarily high bill when the asset is sold. This issue frequently complicates situations involving:

    • A primary residence that has substantially appreciated over time
    • Highly valued investment real estate or family land
    • Stocks, mutual funds, or business interests held for the long term

    2. Assuming Gifting Always Reduces Estate Taxes

    While gifting shrinks the overall size of an estate, that doesn’t always translate into a net financial win for your family.

    Virginia does not impose a state-level estate or inheritance tax, meaning residents only need to plan around the federal estate tax exemption. With the federal unified lifetime exemption sitting at a generous $15 million per individual (and $30 million for married couples), per the IRS’s 2026 estate and gift tax update, the vast majority of Virginia families will never owe a federal estate tax.

    For individuals whose estates fall comfortably below that threshold, shrinking the estate yields no estate tax savings. Instead, it can strip your heirs of the massive capital gains tax savings provided by a stepped-up basis. The goal should always be minimizing your total tax exposure across all tax types.

    3. Ignoring the Gift Tax Rules

    The Internal Revenue Service (IRS) allows individuals to transfer a set amount of assets per recipient each year under the annual gift tax exclusion without filing paperwork. For 2026, this limit is $19,000 per recipient (or up to $38,000 for married couples utilizing gift splitting), as set out by the IRS.

    However, failing to account for these rules can cause compliance headaches:

    • Gifts exceeding the $19,000 limit per person require filing a Form 709 Gift Tax Return.
    • Large lifetime transfers reduce your overall $15 million lifetime estate tax exemption.
    • Failing to file required returns can lead to IRS audits and compliance penalties down the road.

    Filing a gift tax return doesn’t necessarily mean you will owe tax out-of-pocket today, but it is a strict legal tracking requirement that must be managed before making large transfers.

    4. Adding a Child to the Deed Instead of Planning the Transfer Properly

    Many parents add an adult child’s name to the deed of their home as a joint owner, thinking it’s a quick, no-cost way to skip probate. In practice, this move can create as many problems as it solves.

    It’s treated as a present gift of a partial interest in the home, which means the portion given away carries the same carryover basis issue described in Mistake 1. It exposes the home to the child’s creditors, a divorce settlement, or bankruptcy proceedings, since the child now holds a legal ownership interest the parent can’t unilaterally undo.

    It can complicate Medicaid planning, since adding a joint owner is itself a transfer that may need to be disclosed and reviewed under the look-back rule. It doesn’t always avoid probate the way people expect, particularly if the child predeceases the parent or other children are left off the deed, which can create friction among siblings later.

    A deed change is not a substitute for a coordinated estate plan. Whatever the underlying goal, probate avoidance, tax planning, or providing for a specific child, it’s worth discussing with an attorney before retitling property.

    5. Overlooking Medicaid Eligibility and the Look-Back Rule

    Gifting can directly affect Medicaid eligibility, particularly for those planning for long-term care. An important rule to understand is the 5-year (60-month) Medicaid look-back period in Virginia, set out in 12VAC30-40-300, which allows state agencies to review certain asset transfers made before an individual applies for benefits. If assets are transferred below fair market value during that time:

    • A penalty period will be imposed.
    • Eligibility for benefits will be delayed, often by months or years.
    • Access to essential medical assistance services could be cut off, leaving your family to pay out-of-pocket.

    Medicaid also considers strict asset limits, countable assets, and spend-down requirements. For married couples, coordinating asset transfers while protecting a community spouse (the spouse remaining at home) requires highly technical legal structuring. A casual gift to a child today can jeopardize your medical care tomorrow.

    Key Estate Gifting Terms Explained

    6. Giving Up Control Too Soon

    Once you legally transfer ownership of an asset, your authority over it terminates. This loss of control can directly threaten your lifestyle and independence, impacting:

    • Your legal right to live in or manage your primary home
    • Your access to emergency funds if your personal financial health changes
    • Your ability to stop the asset from being seized by a child’s creditors, an ex-spouse in a divorce, or bankruptcy proceedings

    For example, gifting a home to a family member may seem like a straightforward decision. However, you cannot legally force them to let you stay there, nor can you reverse the transfer if your relationship changes. In many cases, utilizing an irrevocable trust or other sophisticated planning vehicles allows you to achieve tax or protection goals without entirely abandoning financial security.

    7. Failing to Coordinate With Your Broader Estate Plan

    An isolated gifting decision can easily trigger an accidental domino effect across your entire estate strategy. Without proper coordination, an unmonitored lifetime gift can:

    • Create accidental inequalities among your children or beneficiaries
    • Short-circuit protective instructions established inside your existing trust documents
    • Disproportionately reduce a surviving spouse’s intended share of assets
    • Interfere with Medicaid planning or spend-down strategies

    Each asset transfer should function as a coordinated piece of your broader plan, rather than a quick fix for an isolated objective.

    Are you seeking an estate planning attorney to help you avoid unexpected tax consequences from gifting mistakes_

    An Example of How Gifting Can Backfire

    Consider this scenario. A parent adds her adult son to the deed of her home as a joint owner, intending to avoid probate. Two years later, she needs nursing home care and applies for Medicaid. Because the deed change counts as a gift of half the home’s value, and it happened within the 60-month look-back period under 12VAC30-40-300, the transfer has to be disclosed and factored into a penalty period.

    If the home is worth $500,000, she gave away an interest worth $250,000. Using a hypothetical average monthly private-pay nursing facility rate of $9,000 for illustration (the actual rate is set annually by DMAS and should be confirmed as of the application date), dividing $250,000 by $9,000 produces a penalty period of just under 28 months during which Medicaid will not pay for her care.

    The deed change meant to simplify things instead delays her access to benefits at the exact point she needs them, leaving her family to cover the cost of care out-of-pocket until the penalty period ends. This example uses assumed values; the actual penalty period in any specific case depends on the property’s value, the number of joint owners, and the DMAS rate in effect at the time of application.

    When Gifting Assets May Make Sense

     
    When Gifting Assets May Make Sense
    Despite the inherent risks, a proactive gifting strategy can be incredibly effective under the right conditions. It may be appropriate if:

    • Your total net worth puts you at risk of exceeding federal estate tax thresholds.
    • You want to move rapidly appreciating assets out of your name so future growth occurs within your children’s estates.
    • You want to provide immediate, targeted financial support to a family member or cover tuition costs.
    • You are making strategic charitable contributions to lower your annual income tax brackets.
    • You are working with an estate planning attorney to structure the transfer safely.

    The defining factor is whether the transfer is structured carefully alongside an estate professional who evaluates the total tax impact first.

    When It May Be Better to Wait

    For many Virginia families, holding onto assets and transferring them through a clear, legally sound inheritance structure produces a safer, more favorable tax position for their heirs. Waiting preserves your options, locks in a stepped-up basis for your heirs, protects your Medicaid eligibility window, and lets you maintain full operational control over your life savings.

    Factors that influence this decision include the specific type of asset, its current market value, its future appreciation potential, and your long-term medical care needs.

    When to Speak With an Estate Planning Attorney

    Gifting decisions touch on federal tax codes, Virginia property laws, and state Medicaid rules all at once. Before signing over a deed or writing a substantial check, consult a legal and financial professional to evaluate:

    • How the transfer affects cost basis and capital gains taxes
    • Whether it impacts Medicaid eligibility requirements and look-back periods
    • Whether alternative strategies (like trusts) could work better for your situation
    • How the decision fits into your comprehensive estate plan

    At PJI Law, PLC, our Richmond, VA estate planning attorneys work with families to evaluate gifting strategies, minimize exposure to capital gains tax, and draft comprehensive estate plans that align with your goals while taking care of your family.

    Searching online for an “estate planning attorney near me” in Richmond, Virginia_

    Frequently Asked Questions

    Is gifting better than inheritance?

    It depends. Inherited property often receives a stepped-up basis, which can reduce capital gains tax, while gifted property may lead to a larger taxable gain.

    Do I have to pay capital gains tax on gifted property?

    A person may need to pay capital gains tax when the property is sold, based on the original cost basis rather than the fair market value at the time of transfer.

    What is the annual gift tax exclusion?

    The annual gift tax exclusion allows you to transfer a certain amount each year ($19,000 per recipient) without filing a gift tax return or reducing your lifetime exemption.

    Does the recipient pay gift tax?

    Typically, the person making the gift is responsible for any gift tax, not the recipient.

    Will gifting assets affect Medicaid eligibility?

    Transfers made within the 5-year look-back period can affect Medicaid eligibility and may lead to penalties.

    What is a stepped-up basis?

    A stepped-up basis adjusts the value of inherited assets to their fair market value at the time of death, which can reduce taxable gain.

    What is a carryover basis?

    A carryover basis means the recipient receives the donor’s original cost basis, which may increase capital gains when the asset is sold.

    Can I gift my primary residence to a family member?

    A primary residence can be gifted to a family member, but doing so may create tax implications, affect control, and impact Medicaid planning.

    Do I need to file a gift tax return?

    A gift tax return may need to be filed if the gift exceeds the annual gift tax exclusion limit.

    Should I talk to a tax professional before gifting assets?

    A tax professional or financial advisor can explain the tax implications so you can avoid costly mistakes.

    Make Gifting Decisions With Your Complete Estate Plan in Mind

    Deciding when and how to gift assets is not just about reducing your estate. It’s about protecting your financial future and your family’s long-term interests. Avoiding these common mistakes can help you make more informed decisions about when and how to transfer assets as part of your overall estate plan.

    At PJI Law, PLC, our Richmond, VA estate planning attorneys sit down with you to map out your assets, your family’s needs, and the tax rules that apply to your specific situation, then build a plan around those details rather than guesswork.

    Call (804) 653-3450 to schedule a complimentary consultation. You can also complete our confidential online form if that is more convenient.

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    4108 E Parham Road
    Richmond, VA 23228
    (804) 653-3450
    https://pjibe.webteam.ai/

  • What Should You Never Put in Your Will in Virginia?

    What Should You Never Put in Your Will in Virginia?

    You create a will to protect the people you care about. You want your assets distributed the way you intended, your family shielded from conflict, and your wishes followed without question.

    What many people don’t realize is that a will can work against those goals when it’s built on common mistakes. The wrong provisions can delay the probate process, trigger disputes among beneficiaries, or lead a Virginia court to disregard parts of your will entirely. In some cases, a single problematic clause can affect how your entire will is interpreted.

    Virginia law sets clear rules for how wills must be written and enforced. When a will conflicts with those rules, the result is often uncertainty, legal challenges, and added stress for your loved ones during an already difficult time.

    So, what should you never put in your will?

    At a Glance

     
    At a Glance

    • Assets with beneficiary designations transfer outside of probate and can’t be redirected by your will.
    • Jointly owned property passes automatically to the surviving owner regardless of what your will says.
    • Funeral instructions in a will are rarely seen in time to be followed.
    • Conditional gifts that conflict with public policy may not be enforceable under Virginia law.
    • Illegal or impossible provisions are disregarded by the court, which can alter how the estate is distributed.
    • Some assets, including real estate and business interests, are often better handled through a living trust.
    • Direct distributions to beneficiaries who rely on government benefits can affect their eligibility.
    • A well-structured estate plan coordinates your will with trusts, beneficiary designations, and other legal documents.

    Do you need the guidance of a lawyer for wills in Fairfax, Virginia_

    What Should You Never Put in Your Will?

    Some assets and instructions simply don’t belong in wills. Others can technically be included but create unnecessary complications that undermine your intentions. The following categories come up often in estate planning, and each carries real risk if handled incorrectly.

    Assets With Beneficiary Designations

    Certain assets pass outside of probate entirely, transferring directly to named beneficiaries regardless of what your will says. These typically include:

    • Life insurance policies
    • Retirement accounts
    • Payable-on-death bank accounts

    When you include these assets in your will, you create a conflict between documents. The financial institution follows the beneficiary designation, not your will. Consider this example: a person updates their will after a divorce and leaves everything to their children, but forgets to update a life insurance policy still naming a former spouse.

    After death, the insurance company pays the former spouse. The will doesn’t change that outcome. This is why beneficiary designations must be coordinated with your overall estate planning strategy.

    Jointly Owned Property

    Property held jointly with rights of survivorship passes automatically to the surviving owner. This often includes:

    • Real estate
    • Bank accounts
    • Certain business assets

    If your will attempts to distribute jointly owned property to multiple beneficiaries, the transfer still happens outside of probate. A parent might add one child to a bank account for convenience, intending to divide that money equally among all children later. After death, that account legally belongs to the one child listed as joint owner, which can lead to disputes.

    This rule extends to vehicles, as well. In Virginia, certain vehicle titles may include transfer-on-death or survivorship designations that allow the vehicle to pass outside of probate, regardless of what your will states. This issue isn’t about intent. It’s about how ownership is structured under Virginia law.

    Funeral Instructions as Binding Terms

    Funeral decisions are made within days of death. A will is often not located, reviewed, or admitted to probate until well after those decisions have already been made.

    A person may clearly state they want cremation and a private service. The family, unaware of those instructions, proceeds with a traditional burial. By the time the will is reviewed, those decisions can’t be undone. Funeral instructions should be communicated directly to loved ones and placed in separate documents where appropriate, not buried in a will that may not surface for weeks.

    Conditional Gifts That Create Legal Problems

    You can include certain conditions in a will, but not all conditions are enforceable. Provisions that attempt to control personal decisions, relationships, or beliefs can conflict with public policy. Examples include:

    • Requiring a child to marry within a specific religion to receive an inheritance
    • Conditioning a gift on cutting ties with a partner
    • Restricting distributions based on personal lifestyle choices

    When a court finds these conditions unenforceable, the result is uncertainty about how the distribution should proceed, even when your intent was clear.

    Instructions That Are Illegal or Impossible

    A will can’t direct actions that violate the law or can’t realistically be carried out. Courts will disregard provisions that attempt to:

    • Avoid estate taxes through improper means
    • Hide or misrepresent assets
    • Distribute property in a way that conflicts with legal ownership rights

    That portion of the will is simply set aside, which can alter how the entire estate is distributed. The risk isn’t just that the provision fails. It’s that the confusion it creates affects the broader administration of the estate.

    Assets Better Suited for a Revocable Living Trust

    Some assets can be placed in a will, but doing so may not be the most effective approach for asset protection and efficient distribution. Real estate, business interests, and other high-value assets often benefit from being placed in a revocable living trust instead. This can help avoid probate and allow for more efficient management.

    When these assets are left solely through a will, they must go through the full probate process in Virginia, which can involve:

    • Court oversight and required filings
    • Delays before beneficiaries receive property
    • Months-long proceedings for each property in the estate

    A living trust provides a different structure that can reduce those delays and give beneficiaries a smooth transition of ownership.

    Business Assets Without a Clear Plan

    Business assets require more than a simple transfer instruction in a will. If you own a business, your estate plan should address:

    • Who will manage the business after your passing
    • Whether ownership will transfer to one person or multiple beneficiaries
    • How decision-making authority will be handled

    Without this planning, the business can face operational challenges at a critical time. A business owner may leave equal shares to several children, assuming they’ll work together. In reality, disagreements arise over management, direction, or whether to sell. Estate planning for business interests requires coordination that goes beyond the will itself.

    Distributions That Affect Government Benefits

    If a beneficiary receives government benefits such as Supplemental Security Income, a direct inheritance can create unintended consequences. A sudden influx of assets can instantly disqualify them from the government benefits they rely on.

    A parent may leave funds directly to a child with special needs, intending to provide financial support. Instead, that inheritance can disrupt eligibility under strict Social Security Administration rules, which restrict cash assistance to individuals with limited income and resources. In these situations, a special needs trust is often the better approach. It allows assets to be used for the individual’s benefit without jeopardizing eligibility.

    Why These Mistakes Lead to Legal Challenges

     
    Why These Mistakes Lead to Legal Challenges

    When a will includes conflicting or problematic provisions, it increases the likelihood of legal challenges. Disputes often arise from:

    • The will conflicting with beneficiary designations
    • Instructions that are unclear or contradictory
    • Family members interpreting provisions differently
    • Concerns about undue influence or intent

    These disputes can bring the estate into court, where a judge must interpret the will and resolve disagreements. The probate process is already structured and formal. When disputes are layered on top, it becomes more time-consuming and more expensive, straining relationships among family members during an already difficult period.

    How the Virginia Probate Process Is Affected

    Probate is the legal process through which a will is validated and an estate is administered. The Virginia Judicial System establishes formal requirements for this process, which unfolds within the Circuit Court of the city or county where the individual resided. In Virginia, this involves:

    • Filing the will with the appropriate Circuit Court Clerk
    • Formal qualification of the executor
    • Identification and valuation of assets
    • Payment of debts and taxes
    • Distribution to beneficiaries

    When a will contains problematic provisions, the court may need to step in, leading to additional filings, delays in distribution, and increased legal costs. In some cases, the court may disregard specific provisions while enforcing the rest of the will, which can change how assets are distributed compared to what the testator intended. Issues that surface during probate often cost more to resolve than they would have cost to prevent.

    Looking for an estate planning lawyer to strategically coordinate your will with trusts for more control_

    How to Structure Your Estate Plan to Avoid These Problems

    A well-structured estate plan uses multiple tools, not just a will. The goal isn’t simply to distribute assets, but to create a plan that works under real-world conditions, avoids unnecessary probate issues, and reduces the risk of disputes.

    Use Beneficiary Designations Strategically

    Keeping designations accurate and aligned with your overall plan matters more than most people realize. To stay on top of this:

    • Review beneficiary designations on life insurance policies, retirement accounts, and payable-on-death bank accounts regularly.
    • Update designations after major life events such as marriage, divorce, or the birth of a child.
    • Confirm that the names listed match your current intentions, not outdated decisions.
    • Coordinate these designations with your will so there are no conflicts.

    If these aren’t aligned, your estate plan is working against itself.

    Consider a Revocable Living Trust for Key Assets

    A revocable living trust can be a powerful tool when your goal is to avoid probate and maintain control over how assets are managed and distributed. Key advantages include:

    • Placing real estate, high-value accounts, and significant assets outside the probate process
    • Naming a trustee to manage assets if you become incapacitated or after your passing
    • Maintaining privacy, since trust assets don’t go through the public probate process

    For larger estates or those with complex property holdings, this approach is often more efficient than relying solely on a will.

    Create a Clear Succession Plan for Business Interests

    If you own a business, your estate plan should address more than ownership transfer. A complete succession plan for business interests should:

    • Identify who will take over management responsibilities.
    • Decide whether ownership will pass to one person or multiple beneficiaries.
    • Establish a buy-sell agreement if there are business partners.
    • Coordinate your will with other legal documents governing the business.

    Without this level of planning, even a well-run business can face serious disruption after your passing.

    Use a Special Needs Trust When Appropriate

    If a beneficiary relies on government benefits, careful planning is necessary. A special needs trust:

    • Allows assets to be used for the individual’s benefit without affecting eligibility for Supplemental Security Income or other programs
    • Gives you the ability to appoint a trustee who understands how to manage distributions properly
    • Supplements rather than replaces essential benefits

    This protects the person you’re trying to support instead of inadvertently creating a financial problem for them.

    Communicate Funeral Arrangements Outside the Will

    To avoid confusion when it matters most:

    • Share funeral arrangements directly with trusted family members.
    • Put written instructions in a separate document that can be easily located.
    • Discuss your wishes in advance so there’s no uncertainty.
    • Consider designating a person responsible for carrying them out.

    This keeps your loved ones from having to guess during an already difficult time.

    Coordinate All Legal Documents Into One Plan

    Your will is only one part of your estate planning strategy. It should work together with:

    • Trusts and beneficiary designations
    • Account ownership structures
    • Other legal documents addressing debts, taxes, and executor authority

    Revisit your plan periodically to reflect changes in your life, assets, and family structure. When everything is coordinated, your estate plan functions as a complete system rather than a collection of disconnected documents.

    The Risks of DIY and Online Template Wills

     
    The Risks of DIY and Online Template Wills

    DIY wills and online templates are often marketed as simple solutions. In reality, they can create serious legal risk. These documents aren’t tailored to your situation or to Virginia law, and they often fail to account for how assets are titled, how beneficiary designations operate, or how the probate process works.

    Common issues include:

    • Missing or improper witnesses
    • Lack of a self-proving affidavit
    • Vague or conflicting provisions
    • Failure to coordinate with other legal documents

    A person may complete a template will that appears valid on its face. After death, the document could create confusion because it attempts to distribute assets that pass outside of probate, conflicts with beneficiary designations, and/or doesn’t address debts clearly.

    Family members may disagree about how to interpret the will, and the matter ends up in court. Consulting a Virginia estate planning attorney rather than relying on a template or acting as your own lawyer is one of the most effective ways to avoid this outcome.

    What Virginia Law Says About Enforceable Wills

    Virginia will requirements are straightforward on paper, but easy to get wrong without proper legal guidance. The Code of Virginia outlines requirements a will must meet to be valid. To be enforceable, a will must generally:

    • Be signed by the testator
    • Be witnessed by at least two individuals
    • Reflect the testator’s intent
    • Be created without undue influence

    A self-proving affidavit can help streamline the probate process by confirming the will’s validity without requiring witnesses to appear in court.

    Knowing what invalidates a will in Virginia is just as important as knowing how to create one. Even when a will meets execution requirements, specific provisions may still be unenforceable if they conflict with the law or public policy. Compliance isn’t just about proper execution. It’s about structure, education around your options, and alignment with legal standards that govern how Virginia courts interpret testamentary documents.

    Common Mistakes That Lead to Disputes Among Family Members

    Disputes rarely arise from one issue alone. They develop from a combination of unclear planning and unmet expectations. Common problems include:

    • Leaving unclear distribution instructions
    • Failing to address prior financial support given to one child
    • Overlooking changes in family structure
    • Not updating documents after major life events

    When these issues are present, family members may interpret the will differently, which can delay the probate process, increase costs, and affect relationships for years. The majority of these disputes are preventable. They stem not from bad intentions, but from estate plans that weren’t built to account for real-world complexity.

    What Belongs in Your Will

    How Proper Estate Planning Protects Your Wishes

    Estate planning is about more than distributing assets. It’s about creating a plan that works when it counts. A thoughtful plan can:

    • Reduce the likelihood of legal challenges
    • Help avoid probate where appropriate
    • Provide asset protection for valuable property and business interests
    • Give beneficiaries a clear path forward

    When each element is structured properly, your wishes are more likely to be carried out as intended.

    Frequently Asked Questions

    Can a will override beneficiary designations?

    No. Beneficiary designations control those assets regardless of what your will states.

    Can you include bank accounts in a will?

    You can only include bank accounts in a will if they don’t already have payable-on-death designations. If they do, the designation controls the transfer.

    What happens if part of a will is invalid?

    A court may disregard that portion and enforce the rest of the will, but this can affect the overall distribution of the estate.

    Can a will affect government benefits?

    Yes. Direct distributions can affect eligibility for Supplemental Security Income and other government benefits.

    Do you need an estate planning attorney?

    While not legally required, working with an estate planning attorney rather than acting as your own lawyer helps reduce errors, avoids common pitfalls, and produces a plan built around your specific situation and Virginia law.

    Searching online for a wills and trusts attorney in Fairfax, Virginia_

    Build a Will That Holds Up When It Counts

    A will should give your loved ones clarity, not leave them facing confusion, delay, or court involvement. Including the wrong provisions can delay probate, create disputes, and leave your family facing challenges that could have been avoided.

    At PJI Law, PLC, we work with clients across Fairfax and Northern Virginia to build estate plans that reflect their intentions and align with Virginia law. Our estate planning attorneys take the time to review your assets, beneficiary designations, business interests, and family structure so your plan works as intended.

    Whether you’re creating your first will or revisiting an existing one, our team will help you avoid the mistakes that can undermine your entire estate plan.

    Call (703) 865-6100 or contact us online to schedule your complimentary consultation today.

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    3900 Jermantown Road, 2nd Floor
    Fairfax, VA 22030
    (703) 865-6100
    https://pjibe.webteam.ai/

  • Should You Put Your Horse in a Trust? A Practical Guide to Equine Estate Planning in Virginia

    Should You Put Your Horse in a Trust? A Practical Guide to Equine Estate Planning in Virginia

    Equine estate planning is a specialized, high-touch service for owners who expect professional, long-term care for their horses—whether those horses are elite competitors, breeding stock, or valuable stablemates. Virginia law permits trusts for the care of animals alive during the settlor’s lifetime.

    A well-crafted equine trust gives you enforceable control over funding, care standards, and succession, and it protects the animal’s welfare and your legacy in a way a simple will cannot.

    Why an Equine Trust is Different from Ordinary Pet Planning

    Horses require specialized facilities, trained caregivers, ongoing farrier and veterinary care, transport, and sometimes insurance and registration management. For owners who invest in top-tier care, estate planning should be equally bespoke.

    A will can transfer ownership and leave money, but it does not create enforceable obligations relative to how funds are spent or how care is provided. An equine trust places funds under fiduciary management and creates legal accountability for the horse’s care for as long as the trust specifies.

    How an Equine Trust Works in Virginia

    Key roles

    • Settlor: the owner who creates the trust and sets the terms.
    • Trustee: the fiduciary who manages the trust assets and disburses funds.
    • Caregiver: the person or facility responsible for daily care and stable management.
    • Enforcer: an optional appointee who can monitor compliance and bring issues to court if necessary.
    • Remainder beneficiary: who receives any remaining funds when the trust terminates.

    Virginia law allows trusts for the care of animals alive during the settlor’s lifetime and provides mechanisms for enforcement, as set out in Va. Code § 64.2-726. That legal structure is what makes an equine trust a reliable, professional solution.

    Practical Considerations for Horse Owners

    Funding and duration

    Horses can live decades and their annual upkeep varies widely. Funding should reflect realistic, location-specific costs: boarding or private stable maintenance, farrier work, routine and specialty veterinary care, feed and supplements, transport, and emergency care. For high-performance or breeding stock, include costs for training, competition travel, and insurance.

    Caregiver and facility requirements

    Name a caregiver who has access to appropriate facilities or the means to secure them. Specify facility standards, turnout routines, exercise, farrier schedules, and veterinary providers. Consider naming a professional stable manager or boarding facility as caregiver, and identify a backup caregiver with equivalent resources.

    Trustee selection

    Choose a trustee with financial competence and, ideally, familiarity with equine care or access to equine advisors. Many owners use a professional trustee or a team approach: a corporate or professional trustee for asset management and an equine-savvy individual or organization to advise on care decisions.

    Special provisions for valuable horses

    Include instructions for registration papers, transfer of ownership for sale or breeding, handling of liens or outstanding bills, and protocols for sale or retirement. Address whether the horse may be sold if funds are insufficient, and set standards for acceptable buyers or facilities.

    Multiple horses and allocation

    If you own multiple horses, specify how funds are allocated, whether one caregiver will manage all animals, and how to handle staggered survivorship. Define priorities for care and distribution of remaining funds when the last covered horse passes.

    Drafting Tips for a Boutique Equine Trust

    • Be specific about routines, providers, and facility standards.
    • Separate roles: appoint a trustee who manages money and a caregiver who manages daily care.
    • Name an enforcer to maintain compliance with your standards.
    • Include contingencies for caregiver incapacity, cost inflation, and relocation.
    • Address documentation: registration papers, health records, and transfer instructions.
    • Consider professional services: boarding contracts, equine insurance, and a professional trustee.

    These elements turn an ordinary trust into a tailored, enforceable plan that preserves both the animal’s welfare and your investment.

    Step-by-Step Setup Checklist

    1. Inventory the horse’s characteristics: competition level, breeding value, age, health, registrations.
    2. Estimate realistic funding: obtain quotes or start from your current expense records for boarding, farrier, vet, transport, and insurance.
    3. Select caregiver and backup: confirm willingness and facility access.
    4. Choose trustee and enforcer: consider a professional trustee plus an equine advisor.
    5. Draft detailed care standards: routine care, medical protocols, end-of-life decisions.
    6. Plan for contingencies: caregiver incapacity, cost increases, sale protocols.
    7. Execute the trust and integrate with your estate plan: coordinate with wills, powers of attorney, and business or breeding agreements.

    Frequently Asked Questions

    Can an animal be a legal beneficiary?

    Animals are not traditional beneficiaries under Virginia law, but the law allows a trust to be created for animals alive during the settlor’s lifetime and funded for their care.

    How much funding should I allocate to an equine trust?

    Funding depends on the horse’s needs, your standards, and your other estate planning objectives. For high-performance or breeding stock, plan for higher annual costs and include contingencies for major medical events.

    Who should I name as trustee and caregiver?

    Many owners use a professional trustee for asset management and a qualified stable manager or boarding facility as caregiver. Naming backups and an enforcer is essential.

    What happens when the horse dies?

    A properly drafted equine trust addresses this directly. When the last covered animal passes away, the trust terminates. Outstanding expenses tied to the horse’s care are paid first, and any remaining funds go to the remainder beneficiary you named in the trust instrument. A clear termination plan prevents disputes so funds are distributed as you intended.

    Who enforces an equine trust?

    The trustee manages funds and holds primary responsibility. Under Va. Code § 64.2-726, Virginia law also allows the court to appoint an enforcer, and anyone with a sincere interest in the animal’s welfare can ask the court to review the trust’s management.

    Can I include a trust protector?

    Yes. A trust protector can be named to oversee the trust and act if issues arise between the trustee and caregiver.

    What if my caregiver can’t serve?

    Your trust can name backup caregivers or give the trustee authority to appoint a qualified replacement if circumstances change.

    Does a trust cover incapacity?

    Yes. A properly drafted trust can take effect while you are still living, not just after your death.

    What happens to leftover funds after the trust ends?

    After the last covered animal passes away and outstanding expenses are paid, any remaining funds are distributed to the remainder beneficiary named in the trust.

    What happens without a plan?

    Without an estate plan that addresses your horses, decisions fall to whoever is left trying to sort things out. That can mean family members disagreeing about who should step in, no clear source of funds for ongoing care, or a valuable horse being moved to a facility that does not meet your standards. For animals with higher maintenance needs, like horses, the stakes are higher. The longer an animal’s expected lifespan and the more specialized its care, the more important it is to have a written, enforceable plan.

    My horse isn’t a high dollar show horse. Should I still consider an equine trust?

    Yes, for the reasons just described. All these factors apply as much to companion horses as competition horses. At PJI Law, our estate planning attorneys create equine trusts specifically tailored to our client’s circumstances and needs.

    I may pay the bills for the horse, but my minor child is the rider in the family.  Does this change anything?

    This gives you one more reason to consider including an equine trust as part of your estate plan. This is your opportunity to take steps to make sure that, should the unexpected occur, your child’s grief will not be compounded by losing horses and riding as a result of losing you.

    Build a Plan for the Animals Who Depend On You

    At PJI Law, PLC, our Northern Virginia estate planning attorneys work with clients who want real protection for the animals in their lives. Whether you have a horse, a dog, a cat, or multiple animals, your plan should reflect the actual cost of care, the people involved, and the instructions that carry your wishes forward.

    We structure equine trusts as part of a comprehensive estate plan, coordinate your assets, and draft clear guidance so care continues without disruption if something happens to you. Each plan is structured under Virginia law to reflect your specific circumstances and goals.

    To put a plan in place or talk through your options, schedule a consultation with PJI Law today by calling (703) 865-6100 or completing our confidential online form.

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    3900 Jermantown Rd, 2nd Floor
    Fairfax, VA 22030
    (703) 865-6100
    https://pjibe.webteam.ai/

  • Why a Power of Attorney for a College Student is Needed Before Move-In Day in Richmond, VA

    Why a Power of Attorney for a College Student is Needed Before Move-In Day in Richmond, VA

    Most families spend months getting ready for college move-in day. You research the school, coordinate housing, handle tuition payments, and make sure your child has everything they need. What most Richmond families don’t think about until it’s too late is the legal gap that opens the moment your child turns 18.

    If you’re wondering why a power of attorney for a college student matters, the answer is this: Once your child becomes a legal adult, you lose the authority to act on their behalf. That loss is immediate under Virginia law, regardless of whether you’re paying tuition, you’re carrying them on your insurance, or they’re listed as an emergency contact.

    If your child is already in college and these documents aren’t in place, it’s not too late. Any college student over 18 can execute these documents at any time, and there’s no reason to wait until the next move-in day to get them in order.

    At a Glance

    At a Glance

    • What this is: Legal documents that authorize you to act for your child after they turn 18
    • Why it matters: Without them, you may be legally unable to make medical or financial decisions in a crisis
    • What you need: A Financial Power of Attorney, an Advance Medical Directive, and a HIPAA Authorization
    • Who is involved: Your child as the principal (the one granting authority) and you as the authorized representative
    • When to act: Before move-in day in Richmond, Virginia

    What Changes the Moment Your Child Turns 18

    Under Virginia law, your child becomes a legal adult at 18. That single change has real consequences, and most families don’t discover them until they’re facing a medical crisis or financial emergency.

    Before your child turned 18, you had the legal authority to access their medical records, speak with their doctors, manage their finances, and make decisions on their behalf. After they turn 18, that authority is gone. It doesn’t matter that you’re their parent. Hospitals, banks, and universities are bound by federal and state privacy laws that treat your child as an independent adult.

    Specifically, you may find yourself unable to:

    • Access your child’s medical records under federal privacy law
    • Speak with doctors or healthcare providers about their condition
    • Make health care decisions if your child is unconscious or incapacitated
    • Access or manage their bank account
    • Handle financial transactions on their behalf
    • View grades, financial aid details, or disciplinary records, which are protected under FERPA, the federal privacy law that governs academic records at colleges and universities

    Most parents are surprised to learn that paying tuition doesn’t give them any automatic right to see their child’s grades or speak with the financial aid office. Once your child turns 18, those records belong to them under federal law, regardless of who is footing the bill.

    This isn’t a theoretical concern. Families across Richmond face these barriers each year when something unexpected occurs. The legal system isn’t designed to make exceptions for well-meaning parents without the proper paperwork in place.

    Seeking a lawyer for Power of Attorney and Advance Medical Directives for your college student in Richmond_

    Why This Matters More Than Most Families Realize

    Why This Matters More Than Most Families Realize

    Consider what happens if your child is injured in an accident and taken to a Richmond hospital. You receive a call and drive to the emergency room. When you arrive, you ask about their condition. The hospital can’t tell you. You ask to speak with the treating physician. You’re told they can’t discuss the case without authorization. 

    You try to give direction on treatment. You’re informed you don’t have legal authority to do so. This isn’t the hospital being difficult. It’s the hospital following the law.

    Without a properly executed medical directive and federal privacy authorization, you’re legally a stranger to your child’s healthcare team. The only way to gain authority at that point may be through a court guardianship proceeding, which takes time, costs money, and creates delays at the worst possible moment.

    Families are surprised to learn how quickly this situation develops. The good news is that it’s entirely preventable. Three legal instruments, prepared before move-in day, give you the authority you need to act when it counts. Getting these authorizations in place is one of the easiest things you can do to protect your child before they leave home.

    Three Vital Legal Documents Each College Student Needs Before Move-In Day

    Many families make the mistake of thinking one document is enough. It isn’t. Each covers a different area of your child’s life, and all three need to be in place before move-in day.

    1. Financial Power of Attorney

    A financial power of attorney allows your child to appoint you as their authorized representative to handle financial matters. Under Virginia’s Uniform Power of Attorney Act (Va. Code § 64.2-1600 et seq.), this paperwork can cover a broad range of financial decisions or be limited to specific transactions.

    As the named representative under a financial power of attorney, you may be authorized to:

    • Access and manage their bank account and other funds.
    • Pay tuition, housing costs, and other college expenses.
    • Handle unexpected financial transactions.
    • Manage assets held in their name.
    • File tax returns on their behalf if needed.
    • Communicate with the university registrar, financial aid office, and billing department on your child’s behalf, although schools may still require separate FERPA authorization for access to certain academic records.
    • Sign housing contracts, enrollment forms, or other university paperwork remotely if your child is unable to do so.

    In practical terms, this means you can step in to handle the kinds of administrative tasks that come up during a college career, from resolving a billing dispute to signing a housing renewal when your child is studying abroad or dealing with a health issue. A power of attorney gives you the legal standing to make those requests. Whether a specific university portal or digital system grants you direct access will depend on that institution’s own policies, but having the paperwork in place puts you in a far stronger position to work with the school.

    A durable power of attorney is particularly important for college students because it remains in effect even if your child becomes incapacitated. Without the durable designation, a standard power of attorney terminates the moment your child loses capacity, which is exactly when you need it most.

    2. Advance Medical Directive

    Virginia law allows your child to execute an advance medical directive that names you as their healthcare representative and outlines their wishes for medical treatment. Under Va. Code § 54.1-2983, this paperwork gives you the legal authority to communicate with healthcare providers and make health care decisions if your child is unable to do so.

    As your child’s healthcare representative, you may be authorized to:

    • Speak directly with doctors and specialists.
    • Access medical records and test results.
    • Approve or decline recommended treatments.
    • Make decisions during a medical emergency when your child can’t communicate.
    • Coordinate care across multiple providers.

    Without this paperwork, healthcare providers are legally prohibited from sharing information or accepting your direction, even in a life-threatening situation. Virginia hospitals follow these rules strictly, and Richmond area medical centers are no exception.

    3. HIPAA Authorization

    The Health Insurance Portability and Accountability Act (HIPAA) restricts who can access a patient’s medical information. Even with an advance medical directive in place, a separate HIPAA authorization form is recommended to give providers clear written permission to communicate with you.

    A HIPAA authorization allows providers to:

    • Release medical records directly to you.
    • Discuss your child’s diagnosis, treatment, and progress.
    • Respond to your questions and requests for information.
    • Coordinate with your child’s insurance company on their behalf.

    Without a HIPAA authorization, providers may decline to share even basic information about your child’s condition, including whether they’re being treated at all. This paperwork works alongside the advance medical directive rather than replacing it.

    What These Documents Actually Give You

    Together, these three documents give you something no emergency contact designation or parental instinct can provide: legal authority. When something happens, you won’t be waiting for someone to make an exception. You’ll have paperwork that clearly establishes your right to act.

    With all three documents properly executed under Virginia law, you may be able to:

    • Make time-sensitive medical decisions without court involvement
    • Access and share medical records with specialists or insurance providers
    • Manage your child’s finances while they recover
    • Pay bills, handle accounts, and protect against financial disruption
    • Communicate directly with your child’s healthcare team
    • Act on your child’s behalf across a wide range of situations

    The peace of mind that comes with having these legal documents in place is real. You’re not hoping someone will work with you. You have the legal standing to step in.

    What Happens Without These Documents

    What Happens Without These Documents

    If your child turns 18 and leaves for college without these authorizations, you’re operating without a safety net. Most of the time, nothing will go wrong, and you’ll never need them. But if something does happen, the barriers you’ll face are significant.

    Without proper authorization, you may encounter:

    • Hospitals that can’t legally discuss your child’s condition or share records
    • Financial institutions that won’t grant you access to accounts
    • Doctors who can’t accept your direction on treatment decisions
    • University administrators who can’t discuss your child’s academic or financial standing
    • Court proceedings to establish guardianship or conservatorship, which can take weeks and cost thousands of dollars

    The guardianship process in Virginia requires filing a petition with the circuit court, obtaining a guardian ad litem for your child, scheduling a hearing, and waiting for a judge’s order. During that time, critical decisions may be delayed. It’s a process designed for situations where no planning was done in advance, and it’s far more burdensome than preparing the right paperwork before move-in day.

    Do you need a Financial Power of Attorney, Advance Medical Directive, & HIPAA Authorization to handle decisions for your college student in Richmond, Virginia_

    Choosing the Right Representative

    Your child gets to decide who serves as their representative. Most college students name one or both parents. Some also name a backup in case the primary representative is unavailable.

    When your child is deciding who to name, consider:

    • Availability. Can this person drop everything and respond quickly if something happens?
    • Location. Are they close enough to Richmond to act in person if needed? If both parents travel frequently or live far from Richmond, consider naming a trusted local family member or close friend as a backup representative who can respond in person quickly if needed.
    • Judgment. Will they make decisions that reflect your child’s values and wishes?
    • Communication. Can they work with medical providers, financial institutions, and other parties under pressure?

    It’s worth having an honest conversation with your child about who they trust to act on their behalf and under what circumstances. These documents reflect your child’s choices, and they should feel comfortable with whoever is named.

    Virginia Legal Requirements

    Virginia has specific requirements for these documents to be legally valid. Working with a Richmond, VA estate planning attorney helps make sure each one is properly executed and enforceable.

    For a financial power of attorney to be valid under Virginia law, it must generally be signed by your child and acknowledged before a notary public. The Virginia Uniform Power of Attorney Act governs financial powers of attorney and sets out your rights and limitations as the named representative.

    For an advance medical directive to be valid under Va. Code § 54.1-2983, your child must sign it in the presence of two witnesses, who must also sign the directive. The witnesses can’t be the person named as healthcare representative, a relative, an heir, or anyone who would benefit financially from your child’s death.

    Virginia also maintains an Advance Health Care Directive Registry where your child can file the document after signing it. Filing with the registry makes the directive accessible to healthcare providers across the state, which is particularly valuable if something happens while your child is away from home and their providers in Richmond don’t have a copy on file.

    Generic online templates may not meet these requirements. A document that doesn’t comply with Virginia law may be rejected by a hospital, bank, or other institution at exactly the moment you need it accepted.

    College Student Move-In Checklist

    Common Mistakes to Avoid

    Even parents who know these documents exist often make mistakes in how they handle them.

    • Completing only one document. Each covers a distinct area. A financial power of attorney doesn’t give you access to medical records. A HIPAA authorization doesn’t authorize you to manage your child’s bank account. And even if you have both, without an advance medical directive naming you as healthcare representative, you may not have clear legal authority to make or enforce medical decisions on your child’s behalf if they are unconscious in a Richmond emergency room. All three serve different purposes and all three are needed. 
    • Waiting until something happens. Once your child is incapacitated or in a medical crisis, it’s too late to execute these documents. Your child must have legal capacity to sign, which means the paperwork must be prepared while everything is fine. 
    • Using generic templates. Virginia has specific execution requirements. A document that doesn’t meet those requirements may be unenforceable. 
    • Not keeping paperwork accessible. These documents are only useful if you can produce them when needed. Keep originals in a secure but accessible location, provide copies to your child’s healthcare providers if appropriate, and make sure your child knows where everything is stored. 
    • Forgetting to update them. Your child’s circumstances will change over the years of college and beyond. If they move to a different state after graduation, enter a serious relationship, or their financial situation changes significantly, the documents should be reviewed and updated accordingly.

    How This Fits Into a Broader Virginia Estate Planning Strategy

    Most parents don’t think of a college student’s power of attorney as part of estate planning. But under Virginia law, these documents are part of the same framework that governs wills, trusts, and advance directives for adults of any age.

    For Richmond families, creating these documents before move-in day is often the first step in helping your child build their own estate plan. It introduces them to concepts like granting legal authority, naming trusted representatives, and putting their own wishes in writing. It also gives you the opportunity to coordinate your child’s paperwork with your own estate plan, making sure wills, trusts, beneficiary designations, and powers of attorney work together as a unified whole.

    Richmond, Virginia estate planning attorneys who work with families on college preparation can also help you review your own documents at the same time. If your own powers of attorney or advance directives haven’t been updated recently, your child’s move-in day is a natural moment to address that, as well.

    Searching online for a “Power of Attorney lawyer near me

    Frequently Asked Questions

    Q: Do I need an attorney to create these documents in Virginia?

    A: You’re not legally required to use an attorney, but Virginia’s execution requirements are specific, and a document that doesn’t meet them may be rejected when you need it most. Working with a Richmond estate planning attorney helps make sure each document is properly drafted, witnessed, notarized, and enforceable under state law.

    Q: Can I access my child’s bank account without a power of attorney?

    A: No. Financial institutions require written legal authorization. Without a valid financial power of attorney, you won’t be granted access to your child’s account regardless of your relationship to them.

    Q: What happens if my child becomes incapacitated and has no documents in place?

    A: You’d need to petition the Virginia circuit court for guardianship and conservatorship. That process involves legal filings, court hearings, and a waiting period during which you may be unable to act. It’s significantly more time-consuming and costly than preparing paperwork in advance.

    Q: Can my child revoke these documents?

    A: Yes. Your child remains in full control and can revoke or update the paperwork at any time as long as they have legal capacity to do so. Executing these documents doesn’t limit your child’s independence in any way during their day-to-day life.

    Q: Do these documents expire?

    A: They don’t expire automatically, but they should be reviewed periodically. If your child attends college out of state or moves to another state after graduation, it’s worth confirming that the Virginia documents will be recognized there. Virginia documents are often accepted in other states when properly drafted, but an attorney can build in language that strengthens out-of-state recognition and gives your child’s documents a much broader reach.

    Protect Your Child Before Move-In Day

    Between housing assignments, orientation schedules, and everything else on your list, college move-in day arrives faster than most families expect. Legal paperwork is one of the easiest things to overlook, and one of the hardest to fix once something goes wrong. Whether your child is heading to campus for the first time or is already enrolled, the time to act is now.

    At PJI Law, PLC, our Richmond, VA estate planning attorneys have years of experience working with clients and families to protect their loved ones with powers of attorney, medical directives, and HIPAA authorizations for college students heading into their next chapter. We take the time to understand your family’s situation, answer your questions, and prepare paperwork that’ll hold up when it’s needed most.

    Our clients consistently tell us that getting these documents in place before move-in day gave them real peace of mind throughout their child’s college years. We have the experience to handle that process efficiently for your family, as well.

    Call (804) 653-3450 to schedule a complimentary consultation before move-in day. You can also complete our confidential online form on our website if that’s more convenient.

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    4108 E Parham Rd, 
    Richmond, VA 23228
    (804) 653-3450
    https://www.pjilaw.com/

  • Can You Create a Revocable Living Trust for Unmarried Couples in Virginia?

    Can You Create a Revocable Living Trust for Unmarried Couples in Virginia?

    You share a home and finances. You’ve built a life together over time. On the surface, it can feel no different from a married couple. But when you look at how Virginia law treats that relationship, the difference becomes clear.

    If something happens to you, your partner doesn’t automatically inherit your assets, access your bank accounts, or make decisions about your estate. Your family members could step in, the court could get involved, and your partner could be left trying to piece things together during one of the hardest moments of their life.

    To close that gap, many couples turn to legal tools that let them decide who receives their assets and how those assets are handled after death. One of the most common is a revocable living trust.

    So, can you create a revocable living trust for unmarried couples in Virginia? Yes, and for many couples in Virginia, it becomes one of the most effective ways to protect your partner’s access to the assets you intend to leave behind.

    At a Glance

    Virginia law does not extend automatic inheritance rights to unmarried partners the way it does to spouses. Here’s a quick look at what a revocable living trust can do for your situation:

    • Unmarried couples do not have automatic inheritance rights under Virginia law.
    • A revocable living trust allows you to control how your assets are handled.
    • Trusts provide better control over how your assets are distributed and can limit court involvement.
    • You can name your partner as a beneficiary and appoint a successor trustee.
    • Proper estate planning reduces the risk of disputes with family members.
    • A revocable living trust is usually the primary tool for partner protection, though an irrevocable trust may be worth discussing with an attorney, depending on your goals.

    Why Estate Planning Looks Different for Unmarried Couples

    When you’re not legally married, the law treats your relationship very differently from how it treats spouses.

    In Virginia, there is no recognition of common law marriage. Unlike community property states, Virginia does not treat unmarried partners as having shared ownership of community property acquired during the relationship. Your partner has no automatic claim to your property or estate under Virginia law. You can review how Virginia handles inheritance rights for unmarried individuals under Virginia’s intestacy statutes.

    That creates real risks:

    • Your partner may receive nothing if you die without a plan.
    • Your assets may pass to distant heirs instead.
    • Your loved ones could face delays and court involvement through probate proceedings.
    • Decisions about your finances or care may fall to someone else.

    That’s why estate planning for unmarried couples in Northern Virginia requires the same attention and care as any other major financial decision you make together.

    How a Revocable Living Trust Helps Protect Your Partner

    A revocable living trust gives you control over your estate while you’re alive and after your death. Instead of relying on default rules that favor legally married spouses, you decide how your assets are distributed.

    Here’s how that works:

    • You name your partner as a beneficiary.
    • You appoint a trustee to manage the trust.
    • You choose a successor trustee to step in if needed.
    • You outline exactly how your property should pass to your beneficiaries after your death.

    This structure gives you better control over how your assets are distributed, keeps your affairs private, and reduces uncertainty for the people you leave behind. It also directly affects your ability to avoid probate, which can otherwise delay access to bank accounts, personal property, and other assets held in your name, which a spouse may have legal rights to under Virginia law, unlike an unmarried partner.

    Joint Trust vs. Separate Trusts for Unmarried Couples

    One of the most common questions attorneys hear from unmarried couples is whether they can create a joint trust.

    The answer is yes, but the right structure depends on your situation.

    A joint trust may work if:

    • You share significant joint ownership of property.
    • You want a unified estate plan for your assets.
    • Your financial lives are closely connected.

    Separate trusts may be better if:

    • You have different financial goals.
    • You want to keep certain assets or property separate.
    • You have minor children from a prior relationship.
    • You want flexibility in how your estate is handled.

    Married couples and spouses often use joint trusts more easily because Virginia law treats them as a unit. For unmarried couples, the structure requires more deliberate estate planning to avoid unintended consequences, including possible gift tax implications depending on how property is contributed and titled.

    One way to reduce that risk is for each partner to contribute only their own separately owned assets to the trust, rather than commingling property. An estate planning attorney can help you evaluate which approach fits your property, your family, and your long-term goals.

    What Happens If You Do Nothing in Virginia

    If you pass away without a trust or any estate planning documents, your estate follows Virginia’s intestacy laws.

    Under those rules:

    • Your partner does not automatically inherit.
    • Your assets pass to blood relatives (including any children you have with your partner) according to a strict statutory hierarchy that does not include an unmarried partner.
    • The court oversees the process.
    • Unlike a spouse, your partner cannot claim an elective share, which is the right to a portion of your estate regardless of what a will says. Without a trust or other estate planning documents, your partner has no legal claim at all.

    This can lead to conflict, delays, and a distribution of your estate that doesn’t reflect your wishes. Without wills, a revocable living trust, or other estate planning documents, even a decades-long partnership carries no legal weight in Virginia probate court.

    How to Set Up a Revocable Living Trust in Virginia

    Creating a revocable living trust involves more than drafting a document. It requires a coordinated estate planning approach involving your assets, finances, and family situation.

    The basic steps include:

    1. Creating the Trust Document

    You outline your wishes, name your beneficiaries, and define how your assets will be handled. Virginia’s requirements for a valid trust, including the settlor’s capacity and intent to create the trust, are governed by Va. Code § 64.2-720.

    2. Choosing a Trustee and Successor Trustee

    This person manages the trust and carries out your instructions. A successor trustee steps in if you become incapacitated or pass away.

    3. Transferring Ownership of Assets

    You must transfer assets into the trust, a process sometimes called funding the trust. This includes bank accounts, property, and investment accounts. An unfunded trust does not avoid probate or control how those assets are distributed.

    4. Coordinating Beneficiary Designations

    Some assets, like retirement accounts and life insurance policies, pass through beneficiary designations, not the trust. These must be aligned with your overall estate plan to avoid gaps in coverage for your partner.

    5. Reviewing Tax and Legal Considerations

    Most revocable living trusts do not reduce estate taxes directly, though they can offer administrative advantages depending on your tax laws and overall estate planning strategy. Whether an irrevocable trust makes more sense for tax benefits in your situation is worth discussing with an attorney.

    This process works best when you work with an estate planning attorney who understands Virginia law and the needs of clients in Fairfax County and across Northern Virginia.

    Common Mistakes Unmarried Couples Make

    The gap between creating an estate plan and protecting your partner comes down to execution. Even well-structured living trusts can fall short when the details aren’t followed through.

    Common issues to watch for:

    • Failing to fund the trust after creating it
    • Relying only on wills when your property and finances require a broader plan
    • Forgetting to update beneficiary designations after major life changes
    • Assuming your partner has the same legal rights as a spouse without documentation
    • Overlooking creditor exposure, as a revocable living trust does not shield your assets from creditors while you’re alive, since you retain control over everything placed in it

    Unlike spouses, unmarried partners have no automatic fallback under Virginia law. A trust only protects what’s in it, and only if your overall estate planning strategy keeps pace with changes in your life, your property, and your family.

    Trusts vs. Wills for Unmarried Couples

    Both living trusts and wills play a role in protecting an unmarried partner, but they function differently and serve different purposes within your estate plan.

    A will:

    • Goes through probate
    • Requires court involvement
    • Becomes part of the public record
    • Can be challenged by family members or other heirs

    A trust:

    • Keeps your affairs private
    • Allows for more direct distribution of assets to beneficiaries
    • Provides stronger practical protection for a surviving partner by allowing trust assets to pass outside probate

    For unmarried couples, a trust often provides stronger protection than wills alone, particularly because Virginia law gives spouses legal rights that your partner simply does not have without proper estate planning documents in place.

    Wills remain important for property and assets not placed in the trust and for naming guardians for minor children. Most attorneys recommend using both as part of a coordinated plan.

    How Trust Planning Supports Long-Term Protection

    Your life will change. Your estate plan should keep up. A revocable living trust is flexible. You can amend it as your property, finances, and family circumstances change. That’s one of the key differences between a revocable and an irrevocable trust: a revocable living trust can be updated; an irrevocable trust generally cannot.

    Trust planning also works alongside other estate planning documents:

    • A power of attorney for financial decisions and management of property
    • Advance directives for healthcare
    • Updated beneficiary designations for retirement accounts and life insurance policies
    • Coordination with wills to cover any property or assets held outside the trust

    Together, these documents form an estate planning strategy that protects your partner the way Virginia law protects spouses by default, not because the law requires it, but because you chose it.

    Frequently Asked Questions


    Q: Can unmarried couples share a trust in Virginia?

    A: Yes. A joint trust is possible for unmarried couples, but the structure depends on your joint ownership of property, your financial goals, and your overall estate planning strategy. An estate planning attorney can walk you through whether a joint trust or separate living trusts make more sense for your situation.

    Q: Does a trust help with avoiding probate in Virginia?

    A: Yes. The most reliable way to avoid probate in Virginia with a trust is to fund it properly after signing. A fully-funded revocable living trust can reduce or eliminate the need for probate proceedings, allowing your assets and property to pass without court involvement.

    Q: What happens if my partner dies without a will or trust?

    A: Under Virginia’s intestacy laws, the estate passes to legal heirs, not to an unmarried partner. Unlike spouses, unmarried partners have no automatic inheritance rights under Virginia law.

    Q: Do unmarried couples need both a trust and a will?

    A: In most cases, yes. Wills can cover property and assets not placed in the trust and can name guardians for minor children, supporting your overall estate plan.

    Q: Are there tax benefits to a revocable trust?

    A: Most revocable living trusts do not provide direct tax benefits. However, they can support better estate administration and, depending on your circumstances, may work alongside other strategies that address estate taxes. Whether an irrevocable trust offers greater tax benefits is worth discussing with an attorney.

    Q: How is a revocable trust different from an irrevocable trust?

    A: A revocable living trust can be amended or revoked during your lifetime. An irrevocable trust generally cannot be changed once established, but may offer different asset protection or tax benefits. Your attorney can help you evaluate which structure fits your estate planning goals.

    Build a Plan That Protects the Person You Chose

    At PJI Law, our Northern Virginia trust attorneys work with clients to build plans that go beyond basic documents. We structure revocable living trusts, coordinate beneficiary designations, align your wills and property ownership, and make sure your partner is protected the way spouses are protected under the law, through deliberate planning, not default rules.

    Whether you’re in Fairfax County or anywhere in Northern Virginia, we focus on thoughtful planning, clear strategy, and long-term protection for the people who matter most to you.

    If you’re ready to put a plan in place or want to talk through your options, schedule a consultation with PJI Law today by calling (703) 865-6100 or completing our confidential online form.

    At PJI Law, you’ll receive white-glove service and personal attention from a team that treats you like family.

    Copyright © 2026. PJI Law, PLC. All rights reserved.

    The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.

    PJI Law, PLC
    3900 Jermantown Rd, 2nd Floor
    Fairfax, VA 22030
    (703) 865-6100
    https://pjibe.webteam.ai/