Whether you’re stepping back from daily operations, bringing on a new member, adjusting ownership after a life event, or preparing your business for future transitions, changing the ownership of a Virginia LLC involves more than updating a name on paper. It’s a legal process that often requires internal approvals, updated agreements, and, in some cases, filings with the Virginia State Corporation Commission—especially when public records or company control is affected.
If you’re asking yourself, how do I change ownership of an LLC?—you’re likely facing a moment of transition. Whether it’s a planned change or a response to unexpected circumstances, understanding the legal and logistical steps involved is key. In this blog, you’ll learn how LLC ownership works in Virginia and what it takes to complete a transfer properly and confidently.
Why People Form LLCs—and What You Need to Know Before Transferring Ownership
Before we get into the mechanics of changing ownership, it’s important to understand why so many business owners choose to form LLCs in Virginia—and how your company’s structure impacts the steps involved when ownership needs to change.
What Makes the LLC Structure So Appealing?
LLCs (Limited Liability Companies) are popular for a reason. They offer liability protection, tax flexibility, and operational freedom that sole proprietorships and corporations don’t always provide. Here’s what makes them a common choice for Virginia business owners:
- Personal Asset Protection – If the company faces a lawsuit or debt, your home, car, or savings are typically not at risk.
- Pass-Through Taxation – LLC profits and losses usually pass through to members and are reported on personal tax returns.
- Flexible Management Structure – You can run the company yourself or appoint managers—there’s no requirement for a board of directors or shareholder meetings.
- Simplicity and Credibility – LLCs are easier to maintain than corporations but still carry legal credibility with clients, vendors, and financial institutions.
Whether you’re operating a small business in Fairfax, VA, or managing a growing company in Northern Virginia, this structure gives you a balance of control and protection.
Documents That Shape LLC Ownership
Changing LLC ownership in Virginia is not a one-size-fits-all process. The steps you need to take depend heavily on how your company was structured at formation and what internal documents are in place. The following items typically shape how ownership may be changed:
- Articles of Organization – This foundational document officially forms your LLC and is filed with the Virginia State Corporation Commission (SCC). It identifies your registered agent, principal office, and whether the company is member-managed or manager-managed. Changes in ownership alone do not require filing an amendment—unless they affect publicly listed information like the registered agent, business address, or management structure.
- Operating Agreement – While not required by law, the operating agreement governs internal operations, member rights and duties, and procedures for transferring ownership. Under Va. Code § 13.1-1023(A), members may enter into a written or oral agreement covering “the affairs of the limited liability company and the conduct of its business.” If your operating agreement outlines how membership interests may be sold, assigned, or transferred, that language will control.
If no operating agreement exists—or if it’s silent on ownership changes—Virginia law supplies default rules. For example, Va. Code § 13.1-1038.1(A) generally requires majority consent of members to admit a new member, unless otherwise agreed. This means that even a partial interest transfer may require all current members to approve.
- EIN (Employer Identification Number) – Your EIN does not change during a transfer, but if the LLC’s “responsible party” changes, the IRS requires an update.
- Buy-Sell Agreements – These agreements—either within the operating agreement or as standalone contracts—set the terms for how and when membership interests may be bought or sold. They often include provisions for pricing, valuation methods, rights of first refusal, and triggering events like retirement, death, or disability.
- Business Licenses or Permits – Depending on your industry and local regulations, you may need to update licenses or permits if there is a change in ownership or control. This is especially relevant for businesses in regulated professions, those holding ABC licenses, or contractors subject to Department of Professional and Occupational Regulation oversight.
Why LLC Ownership May Change
Ownership changes are common throughout the life of an LLC. They often arise from routine business planning—but can also be triggered by more urgent circumstances. Some of the most common reasons include:
- A member is retiring or withdrawing from the company
- A new investor or partner is joining and acquiring an interest
- An existing member is transferring part or all of their interest to another member or third party
- Death, incapacity, or divorce involving a current member
- Succession or estate planning, particularly for family-owned or closely held businesses
- Business restructuring for tax or liability purposes
Whether the change involves a full buyout or a partial reallocation of interests, it often requires:
- A review of the operating agreement or buy-sell agreement
- A written assignment or transfer of membership interest
- Approval from other members (if required under Va. Code § 13.1-1038.1)
- An update to the LLC’s internal records and, in some cases, its filings with the SCC
Some ownership changes may also prompt the business to convert to a different entity type—for example, if the members decide to form a corporation or partnership to meet evolving needs. These decisions should be made carefully and documented properly to avoid conflict, tax surprises, or regulatory issues later.
How Ownership Changes Work: LLCs With Two or More Members vs. Single-Member LLCs
LLCs with two or more members must follow specific procedures—typically outlined in the operating agreement. For single-member LLCs, the process is more direct but still requires proper documentation and careful recordkeeping.
If Your LLC Has Two or More Members
If your LLC has two or more members (multi-member LLC), the operating agreement typically outlines how ownership interests can be bought, sold, or reassigned. These provisions are legally enforceable under Va. Code § 13.1-1023 and may include:
- Limits on transferring interests to outside parties
- Buy-sell provisions that apply during retirement, death, disability, or divorce
- Voting or approval requirements—some decisions require unanimous consent; others only a majority
- A valuation method for pricing the membership interest
Most Virginia LLCs with more than one member will have an operating agreement in place since it’s strongly recommended by legal and financial professionals. However, if no agreement exists—or if it’s silent on ownership changes—Virginia law provides fallback rules. As noted earlier, this includes the requirement that a majority of current members must agree before a new member can be added—even if someone has already been assigned a share of the LLC’s profits (known as an economic interest).
Before finalizing any ownership change, you should:
- Review your operating agreement or, if none exists, the applicable provisions of Virginia law.
- Obtain any required written approvals.
- Draft and sign a contract documenting the transfer.
- Update your company’s records to reflect who holds what percentage of ownership and what rights they have. This helps avoid confusion over decision-making authority and profit distributions.
If You’re the Sole Member
If you’re the only member of your Virginia LLC, changing ownership may seem simple—but it still requires careful documentation. Whether you’re selling the business, transferring some or all of your interest to a relative, or placing it in a trust for estate planning, each of these is a legal transaction that affects control, tax obligations, and your company’s internal records.
Even without additional members, you still need to:
- Draft a legally binding transfer agreement or assignment of membership interest.
- Update your company’s internal records to show the new owner or beneficiary of the interest. This includes revising any existing operating agreement or creating one if none exists.
- Amend your Articles of Organization if the change affects your registered agent, business address, or management structure
- Update any licenses, contracts, or financial accounts tied to your ownership
Doing this correctly protects both you and the business—especially if the LLC has contracts, liabilities, or ongoing operations. You don’t need to file ownership transfer paperwork with the Virginia SCC unless the change affects publicly filed information, such as your registered agent, business address, or how the LLC is managed.
Document the Ownership Change with a Written Agreement
Once you’ve reviewed your operating agreement and agreed on the terms of the ownership change, the next step is to put it in writing. This written agreement is what legally finalizes the change in ownership. Without a signed agreement, there’s no enforceable transfer—even if everyone involved has agreed informally.
Your written agreement should include:
- The names of the parties involved – including the current member(s) and the person or entity receiving the ownership interest
- What type of change is occurring – is it a full transfer, partial interest sale, or internal reallocation of control?
- The percentage or portion of the LLC being transferred
- The purchase price or value of the interest (if applicable)
- The effective date of the ownership change
- Any continuing responsibilities or limitations related to the transfer
- Non-disclosure or confidentiality provisions, if trade secrets or sensitive business information is involved
- Signatures of all parties, confirming mutual intent
Depending on how your LLC is structured and what’s being transferred, this contract might be called:
- A Membership Interest Purchase Agreement
- An Assignment of Membership Interest
- A Transfer of Ownership Agreement (common for single-member LLCs)
If your LLC has multiple members, you may also need to attach or reference the written approval required under your operating agreement or Virginia’s default rules.
What to Update After the Ownership Change
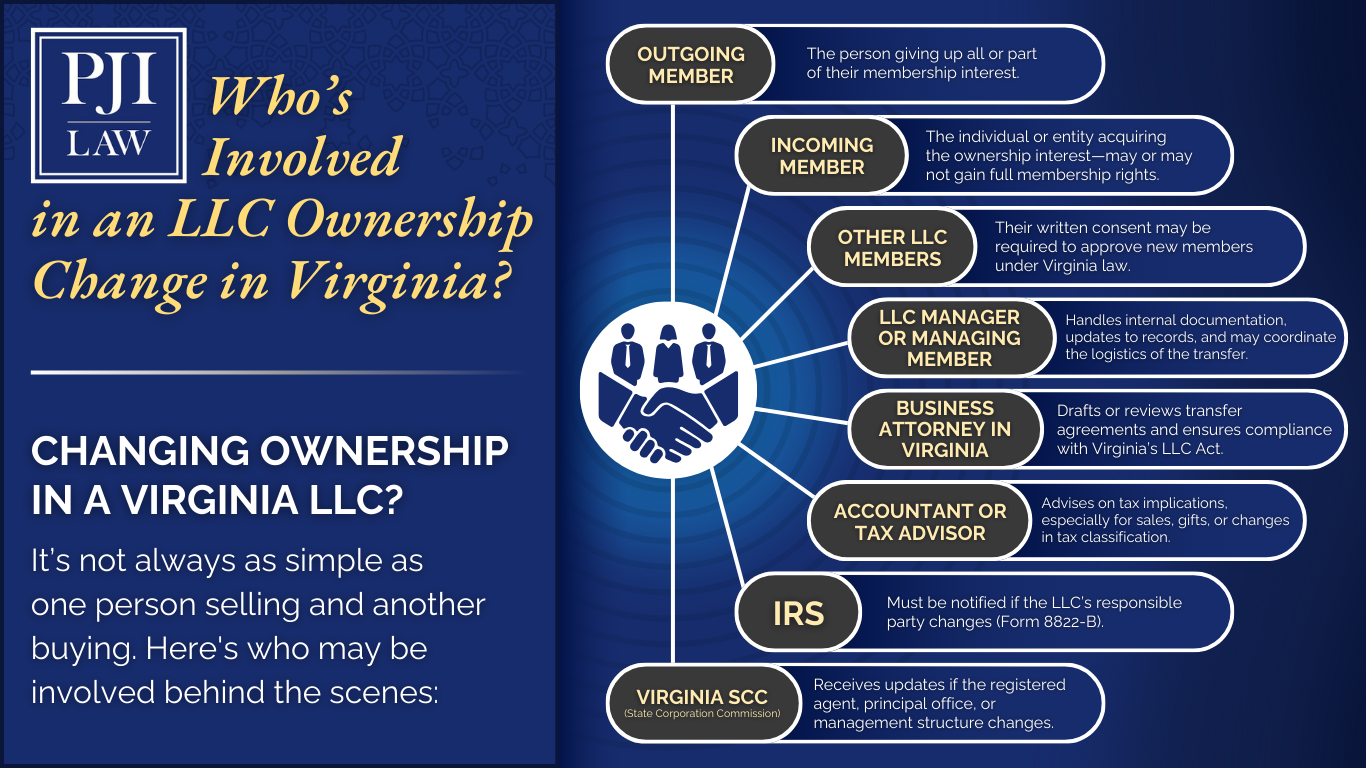
Once the ownership agreement is signed, the legal transfer has taken place—but you’re not done yet. There are still a few critical steps to keep your LLC compliant and avoid headaches down the road. You may need to update your LLC’s public records, tax status, and internal documents to reflect the change in control.
Update the Virginia SCC
You don’t need to file ownership transfer documents with the Virginia SCC unless the change affects public-facing company information. However, you must file an amendment to your Articles of Organization if the change affects:
- Your registered agent or registered office
- Your principal business address
- Your management structure (member-managed vs. manager-managed)
- Your company name, if this change is part of a larger restructuring
You can file these changes through the Virginia SCC Clerk’s Information System. Failing to keep these records current could result in penalties or loss of good standing with the state.
Notify the IRS
If the ownership change results in a new responsible party for the LLC, you must notify the IRS using Form 8822-B. This applies in situations such as:
- Selling the business
- Transferring the LLC to a new individual or entity
- Changing the LLC’s federal tax classification
Failing to update the IRS could lead to tax filing issues, delayed correspondence, or audit complications.
Revise the Operating Agreement
Even if your LLC’s operating agreement doesn’t need to be filed with the state, it should be updated internally to reflect the current ownership. Updates may include:
- Adding or removing member names
- Adjusting ownership percentages
- Revising voting rights or profit-sharing arrangements
- Reflecting changes to succession or withdrawal provisions
Keeping this document current protects the business and clarifies who holds ownership, who has decision-making authority, and how future changes should be managed.
Review and Update Other Records
Ownership changes often trigger other updates across your business operations. Review and revise:
- Local and state business licenses
- Vendor, client, or contractor agreements (some may require notice of ownership changes)
- Leases, insurance policies, or loan agreements
- Bank accounts, check signers, and payment systems
- Payroll services or employee benefits records, if ownership affects employer identity
While not every item on this list applies to every business, it’s wise to review contracts and licenses to confirm whether any terms are tied to specific owners or managing members.
Work With a Virginia Business Attorney to Finalize the Change
Changing ownership in an LLC isn’t just a business decision—it’s a legal transaction with long-term consequences. Even if the transfer seems straightforward, it often involves contracts, tax considerations, and compliance issues that go beyond what’s visible on paper.
A business attorney in Virginia can guide you through:
- Reviewing your operating agreement and determining whether member approval is required
- Drafting a customized ownership transfer agreement that reflects your goals and protects your rights
- Ensuring compliance with state law, including Articles of Amendment filed with the SCC if needed
- Addressing IRS requirements, such as updating the responsible party for your LLC
- Revising or reviewing related contracts, licenses, leases, and business obligations that could be affected by the change
This is especially important if:
- Your LLC has multiple members
- The company owns real estate, intellectual property, or other valuable assets
- The change is part of a divorce, estate plan, or succession strategy
- There are disagreements or unclear terms around valuation, authority, or control
Some business owners attempt to handle the transfer on their own using generic templates or outdated forms. But cutting corners now can create bigger problems later—especially if tax filings are incomplete, SCC records are inaccurate, or your agreement doesn’t fully protect your interests. Whether you’re selling your ownership stake, bringing in a new partner, or restructuring for the future, legal guidance helps you make the change with confidence—and on the right terms.
Changing ownership of an LLC in Virginia involves more than signing a contract or updating a form. It’s a coordinated process that touches nearly every part of your business—from your operating agreement and tax filings to your licenses and contracts. If you’re preparing for this kind of transition, take the legal steps that protect your business and your future.
Changing LLC Ownership in Virginia?
Whether you’re transferring your entire business, adding a new member, or updating your structure for the future, changing ownership in an LLC involves more than a handshake. You need clear contracts, proper filings, and an understanding of how Virginia law applies to your situation.
At PJI Law, we work with business owners across Virginia to prepare and complete ownership changes that hold up both on paper and in practice. We assist with drafting agreements, updating operating documents, filing with the SCC, and addressing tax-related concerns tied to membership interests.
Your online search for a “legal contract lawyer” or “lawyer for business contract” led you here–and you’re in the right place. Take the next step and call (703) 865-6100 or fill out our confidential online form to schedule your consultation today.
At PJI Law, you’ll receive white glove service and personalized attention!
Copyright © 2025. PJI Law, PLC. All rights reserved.
The information in this blog post (“post”) is provided for general informational purposes only and may not reflect the current law in your jurisdiction. No information in this post should be construed as legal advice from the individual author or the law firm, nor is it intended to be a substitute for legal counsel on any subject matter. No reader of this post should act or refrain from acting based on any information included in or accessible through this post without seeking the appropriate legal or other professional advice on the particular facts and circumstances at issue from a lawyer licensed in the recipient’s state, country, or other appropriate licensing jurisdiction.
PJI Law, PLC
3900 Jermantown Rd, 2nd Floor
Fairfax, Virginia 22030
(703) 865-6100
https://pjibe.webteam.ai/